

Annual results from Tristel (AIM: TSTL), the manufacturer of infection prevention products, have once again shown a record performance, with trading in line with both market expectations and internal performance targets for the year to end-June 2026.
The business
Tristel is a global infection prevention company focused on the manufacture and supply of products using its unique proprietary chlorine dioxide (ClO2) chemistry. The company is a market leader in manual decontamination of medical devices, supplying hospitals with products under the Tristel brand, which also encompasses its sporicidal (spore killing) surface disinfection range offered as a sustainable alternative to commonly used pre-wetted plastic wipes.
The firm’s head office and manufacturing facility are located in Snailwell, near Cambridge, but Tristel operates globally, employing 282 people across 19 countries, with 19 subsidiaries selling directly into hospitals and sales into more than 40 countries in total.
Tristel has been one of the more successful AIM companies over the past 21 years. Listing on the market in June 2005 at 37p per share, Tristel currently trades at 435p. The firm targets double digit revenue growth annually, an adjusted EBITDA margin of at least 25%, with the business having no debt and a progressive dividend policy.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Full year numbers
For FY2026, Tristel delivered another year of double-digit revenue growth, strong growth in pre-tax profits and maintained strong cash generation from operations. Revenue was up by 10% to £51.1 million, with growth led by the medical device decontamination business, where sales grew by 11% to £45 million. The Tristel Surfaces disinfection range contributed £4.7 million, up from £3.7 million. The remaining £1.4 million came from non-core sales into the pharmaceutical and personal care manufacturing, veterinary and animal welfare sectors.
With gross margins edging up to 82% from 81%, adjusted pre-tax profits grew by 15% to £11.7 million and reported pre-tax profit was up 30% to £11.0 million. Adjusted EBITDA for the year was £15.7 million, up from £13 million in FY2025, with the margin of 31% being well above Tristel’s 25% target.
As a result of the strong performance the dividend for the full year was increased by 5% to 14.91p per share.
Tristel remained debt free at the period end, with cash and short-term investments amounting to £16 million, up from £12.8 million 12 months earlier, with continued strong net operating cashflow of £11.1 million, up from £10.3 million. Tristel flagged that this enables it to fund planned international expansion, regulatory approvals, clinical evidence, product innovation and digital capabilities while maintaining a commitment to progressive shareholder returns.
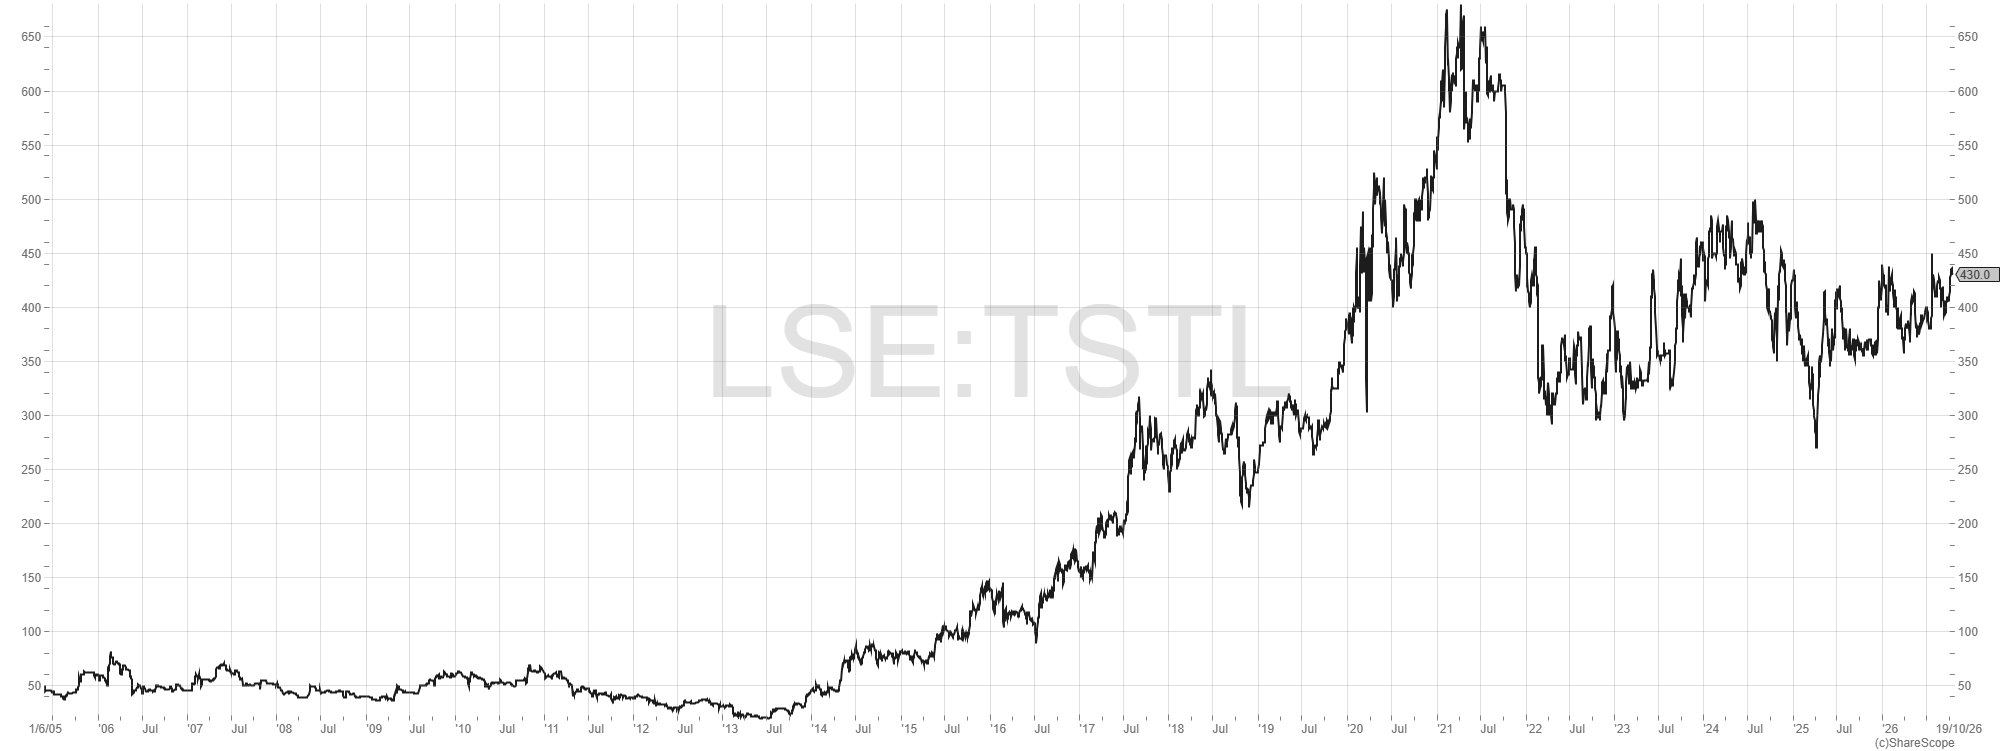
Tristel share price performance since IPO
Operational highlights
By geography, growth was seen across the UK and a number of key European markets during the year. There was a material increased contribution from the United States, a market which Tristel believes is the most significant incremental opportunity available to it, with two FDA-cleared high level disinfectants. The Americas geographical segment, while still modest in absolute terms, grew revenues from £0.3 million to £0.8 million in FY2026 as the firm’s ULT product for ultrasound probes continued to gain traction on the market and ophthalmic devices product OPH brought new revenues post launch early in FY2026.
During the year, Tristel launched new product VISICLEAN™, a coloured cleaning technology designed to provide visible confirmation of the cleaning step and complement its point-of-care ultrasound decontamination workflow. It also completed a transition to in-house wipe manufacturing, with efficiencies from the new production model beginning to emerge.
After the period end, in August, Chris Lee joined as the firm’s new CEO. He has more than 35 years’ experience in the medical technology and healthcare industry and extensive international commercial leadership experience, most recently serving as CEO of Summit Medical, a UK-based medical device group, from 2020 to 2025. Previous CEO, Matt Sassone, left in June to start a worldwide president role with a large US multinational.
Also following the period end, in September 2026, Tristel launched Unifoam, a new drain disinfectant, in the UK. The initial roll-out will extend to France, Germany, Spain and key markets across Asia, with full product availability from January 2027. Tristel has also commercially launched 3T Pro, the premium tier of its digital compliance platform, creating the firm’s first paid 3T offering and a platform for recurring digital revenues.
Outlook
There were no specific numbers on expectations for the current financial year but the firm did say that “The Board remains confident that the Group’s differentiated technology, predominantly consumables based revenue model and significant geographic opportunity provide a strong platform for sustained profitable growth.”
Comment
This was another strong performance from Tristel, with the full year numbers maintaining the excellent record as a public company. The firm has grown revenues from just £3 million in 2005 (the first year of being listed on AIM) to £51.1 million in 2026, that’s a compound annual growth rate of 14.45%. Net profits over the same period have gone from £0.04 million to £8 million and the dividend from 0.5p per share in 2005 to 14.91p for FY2026.
The dividend payment is covered 1.22 times by adjusted earnings for 2026, with the new annual cash cost of around £7.17 million being covered 1.55 times by last year’s net cash flow from operations. The continuing strong cash flow and cash balance of £16 million provides the financial backing to maintain increased payments to shareholders. At the current share price of 435p Tristel is on a historic (adjusted) earnings multiple of 23.9 times and yields a historic 3.42%.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Tristel is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.