

Guitar and piano seller Gear4music (AIM: G4M) grew total revenues by 6% to £85.4 million in the six months to 30th September 2026, so says today’s H1 2027 trading update. Revenue growth in the larger UK business was modest at 3%, to £51 million, with revenues in Europe and the Rest of the World up by a more pronounced 11% to £34.4 million. These figures were in line with expectations and against a very strong H1 2026 which saw total revenues up by 31% to £80.7 million.
The business
Operating from its head office in York, distribution centres in York, Bacup, Sweden, Germany, Ireland & Spain, and showrooms in York, Bacup, Sweden & Germany, Gear4music sells own-brand musical instruments and music equipment alongside premium third-party brands including Fender, Yamaha and Roland, to customers ranging from beginners to musical enthusiasts and professionals, in the UK, Europe and the Rest of the World. Having developed its own e-commerce platform, with multilingual, multicurrency websites delivering to over 190 countries, the company continues to build its overseas presence.
Gear4music listed on AIM in June 2015, raising £10 million at 139p per share.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
H1 trading
Back to today’s trading update and gross margin for H1 2027 is expected to be 27.6%, down slightly from 28.0% in H1 2026 but up on H1 2025’s 26.7%. Gross profit is expected to be £23.6 million, up from £22.6 million in H1 2026 and £16.5 million in H1 2025. EBITDA expected to be £5.7 million, down from £6.5 million in H1 2026 due to setup costs associated with a new automated UK warehouse.
At the time of the FY2026 results announcement in June this year the firm said that the warehouse fit out was progressing well and on schedule to be operational ahead of the FY2027 peak. Today, Executive Chair, Andrew Wass, said, “The development of our new automated UK warehouse continues to progress and is an important part of this investment, with the anticipated initial setup costs reflected in our first-half earnings.”
The company added that it is “well prepared” for the important peak trading period (Christmas), with performance for FY2027 expected to be in line with the market consensus. The full interim results will be out on 17th November.
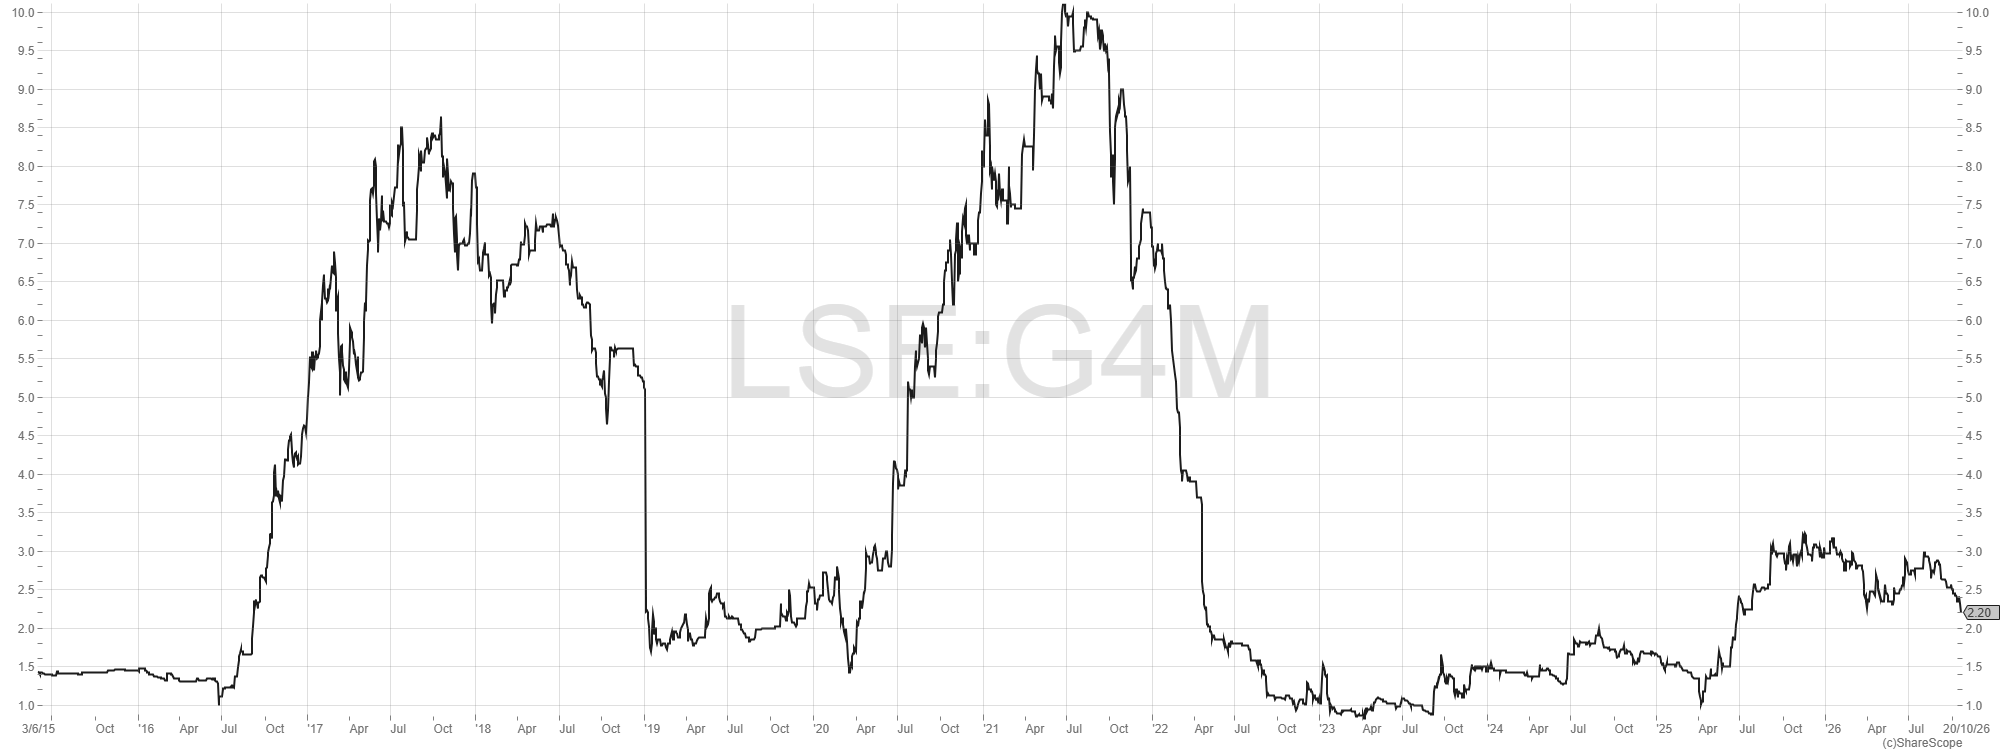
Gear4music share price chart since IPO
Comment
Another good performance from Gear4music, which has an excellent track record as a public company. Annual revenues grew from £35.5 million in FY2016 to £190.7 million in FY2026, with pre-tax profits up from a marginal gain to £10.3 million over the same period. For FY2027 the market consensus is for revenue of £200.2 million, EBITDA of £16.0 million and pre-tax profits of £6.0 million. Those figures imply revenue growth of 5%, an EBITDA fall of 13% and pre-tax profit fall of 41.7% over the FY2026 numbers.
Shares in the company have fallen from almost 300p at the beginning of August to 220p as we write, down 5.4% on the day as investors are seemingly focusing on the profits fall, although the reason for this has been clearly flagged. While the new warehouse is depressing margins in the short-term it does seem a sensible move for a growing company, with its focus being on medium and long-term opportunities. Investors will be looking out for further updates from the company, which is now entering its key Christmas trading period against a challenging environment for discretionary consumer spending.
Overall, we believe that Gear4music is a solid business with further long-term growth opportunities. Management estimate that the top 10 European retail markets for musical instruments and music equipment (including the UK) are worth £5 billion annually, and are undergoing a shift towards online retail, providing plenty more business to go for. We note that founder and Executive Chair, Andrew Wass, recently won the Entrepreneur of the Year Award at the annual AIM Awards ceremony, recognising his successes over the years.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Gear4music is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.