

Shares in Hardide (AIM: HDD) have gained 8.2% to 112.5p after the provider of advanced surface coating technology announced a positive trading update for the year to 30th September 2026.
Revenues more than doubled in the year, from £6 million in FY2025 to £13.5 million. EBITDA is expected to be £5.8 million, up from £1 million, with pre-tax profits of £4.9 million against FY2025’s modest gain of £0.2 million. The profit figures were both slightly ahead of market expectations (EBITDA of £5.5 million and pre-tax profits of £4.6 million) as a result of improved cost management and continuous improvement initiatives.
The business
Hardide was formed in 2000 by a team of UK venture capitalists to develop and commercialise a patent for the Hardide Chemical Vapour Deposition (CVD) coating process.
As of today, the firm develops, manufactures and applies advanced technology tungsten carbide/tungsten metal matrix composite coatings to a wide range of engineering components. Its patented technology is unique in combining in one material, a mix of toughness and resistance to abrasion, erosion and corrosion, together with the ability to coat accurately interior surfaces and complex geometries.
The material is proven to offer dramatic improvements in component life, particularly when applied to components that operate in very aggressive environments. This results in cost savings through reduced downtime and increased operational efficiency as well as a reduced carbon footprint. Customers include leading companies operating in the energy, valve and pump manufacturing, industrial gas turbine, precision engineering and aerospace industries.
The business listed on AIM in 2005, opened a US facility in Martinsville, Virginia, to process parts for customers in North America in 2016, and in 2020 moved to a new site in Bicester, Oxfordshire, which doubled the size of its UK facility.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Trading remains strong
Back to today’s update, trading momentum is said to be strong. Final quarter revenue was £4.6 million (34% of FY2026 revenues), generating EBITDA of c.£1.9 million (33% of annual EBITDA). As announced on 14th September, the firm successfully delivered the first shipments of coatings for a new generation of parts for its major North American customer, leading to a further US$1.9 million (c.£1.4 million) sales order covering the period to November 2026.
Hardide has also recently won further production work in the aerospace sector, together with new customer wins in the energy and industrials sectors, all of which will contribute to revenues in FY2027. Testing continues across a number of applications with a potential major energy sector customer in the Middle East, as well as customers in the semi-conductor sector, with results to date said to be encouraging.
On the balance sheet, gross cash as at 30th September 2026 was £3.2 million, up from £0.7 million a year earlier despite making a £1.5 million investment in working capital. This was to support growth and to secure process gas supplies covering the majority of FY2027’s anticipated requirements at known costs. In addition, a deposit of £0.7 million has been paid for coating reactors with a total expected cost of £3.5 million which, as previously announced, are expected to double Hardide’s operational capacity to c.£40 million of annual sales. The new capacity is scheduled to come on stream during the second half of FY2027.
On the outlook, the firm said that the combination of strong current trading momentum and encouraging recent order intake underpins market expectations and positions the company for further significant growth in FY2027, consistent with its strategic objective of more than doubling revenues again over the next two to three years. The full-year results will be announced on 10th December. Market expectations for FY2027 are for revenue of £18.8 million, EBITDA of £8.0 million and pre-tax profits of £6.6 million.
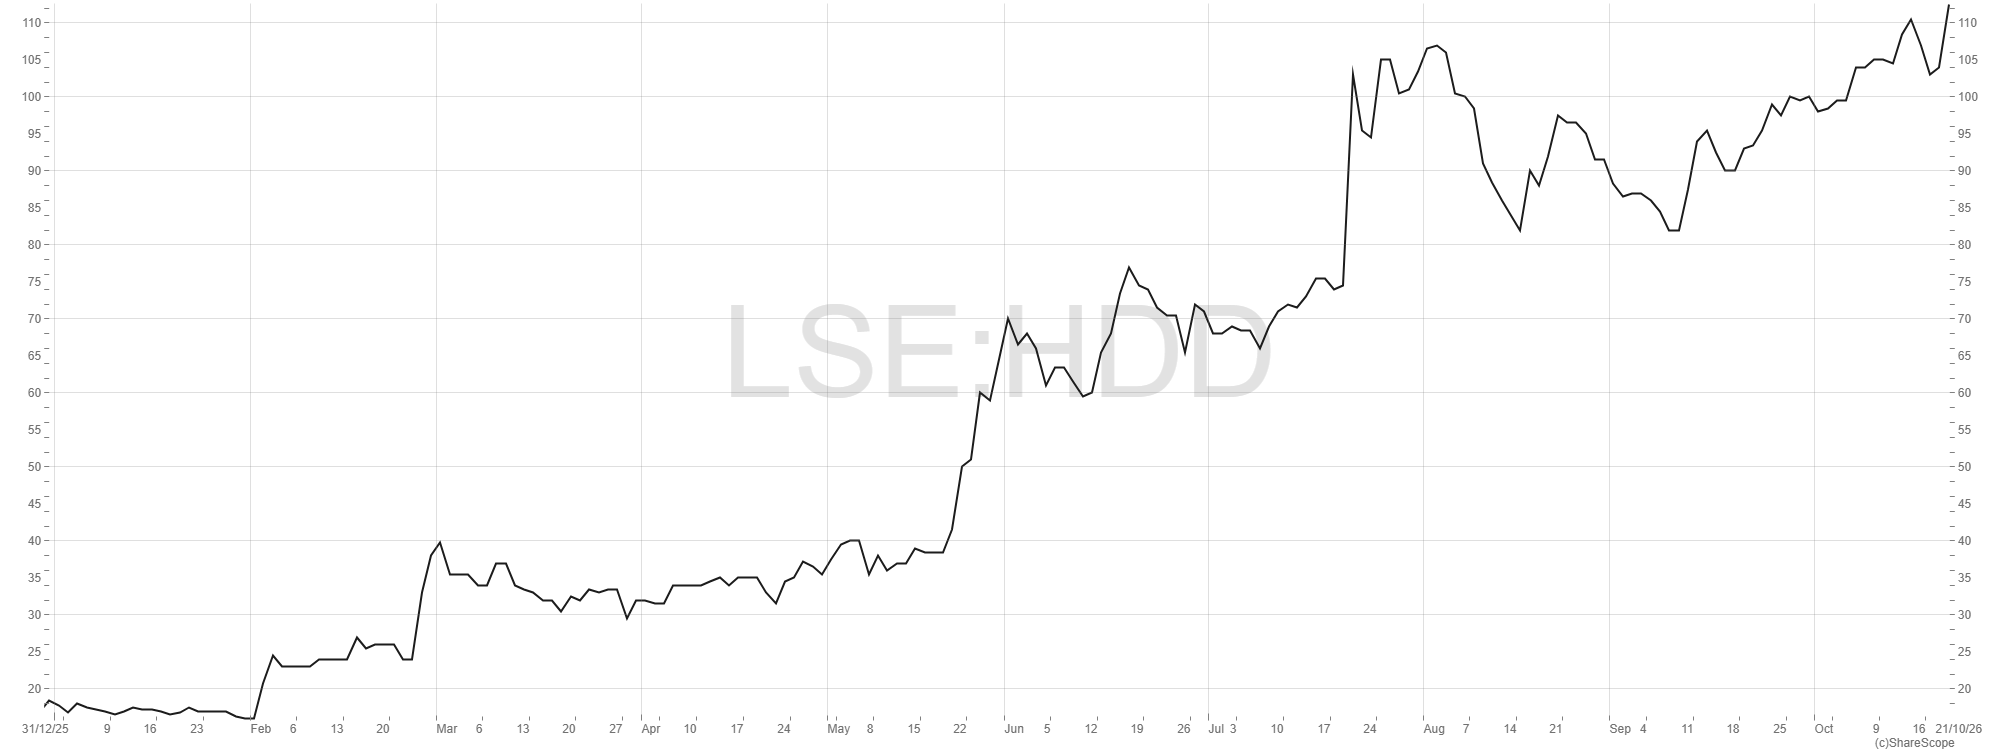
Hardide share price performance year to date
Comment
This is another encouraging performance from Hardide, a business which has been modestly loss-making for most of its time as a public company. FY2026 was the first year that revenue hit double digits, and pre-tax profits of £4.9 million even exceed revenues for the whole of 2024 (£4.7 million).
Trading has really taken off this year following sustained new business momentum, including major contract wins with a North American energy customer. Today’s modest forecast-beating statement comes after the firm announced in July that the full-year financial performance would be materially ahead of its previous expectations. Hardide also upgraded in April and February.
At the current price of 112.5p, the shares are at a level not seen since June 2008, giving Hardide a market cap of £88.7 million.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Hardide is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.