

Tortilla Mexican Grill - raises £2.5 million to repay overdraft and accelerate growth plan
Fast-casual Mexican restaurant business Tortilla Mexican Grill (AIM: MEX) has completed an equity fundraise of £2.5 million, at a price of 65p per share, after announcing the deal after hours yesterday. The raise was done at a discount of 8.5% to yesterday’s closing price, with the new shares representing c.9% of the enlarged share capital.
Richard Haley, CFO, put c.£33k into the raise, buying 50,715 new shares, and Jennifer Roebuck, wife of Founder & CEO Brandon Stephens, bought 117,932 new shares for c.£77k.
Tortilla will use the net proceeds of the funding to repay a £1.3 million incremental short-term overdraft facility, to give it working capital headroom of £1.1 million and additional cash to accelerate the execution of its Value Creation Plan (VCP). In particular, the strengthened balance sheet will provide the company with headroom under its net leverage banking covenant, providing some flexibility should trading take an unexpected hit. The firm added that it’s forecast to remain within all of its bank covenants at each quarterly test date but headroom is sensitive to trading performance.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
The business
Founded in 2007, Tortilla Mexican Grill is Europe’s largest fast-casual Mexican restaurant brand. Through the acquisition of burrito business Chilango in the UK in 2022 and Fresh Burritos in France in 2024, as well as franchise partnerships with SSP Group and Compass Group UK & Ireland in the UK, and Eathos in the Middle East, the brand continues to expand globally.
The group currently operates 64 corporate restaurants and 15 franchised restaurants in the UK, eight corporate restaurants and seven franchised restaurants in France, and 12 franchised restaurants in the UAE, giving a total estate of 106 sites.
Tortilla combines quick-service with quality ingredients to serve affordable, made-to-order meals in under 90 seconds, in cosy environments catering for lunch or dinner, and for beers with friends. The menu is fully customisable, with thousands of flavour combinations to try, and features only higher welfare meats. Toppings are prepared using fresh ingredients that are free from artificial flavours and preservatives, with 70% of the toppings plant-based and vegan-friendly.
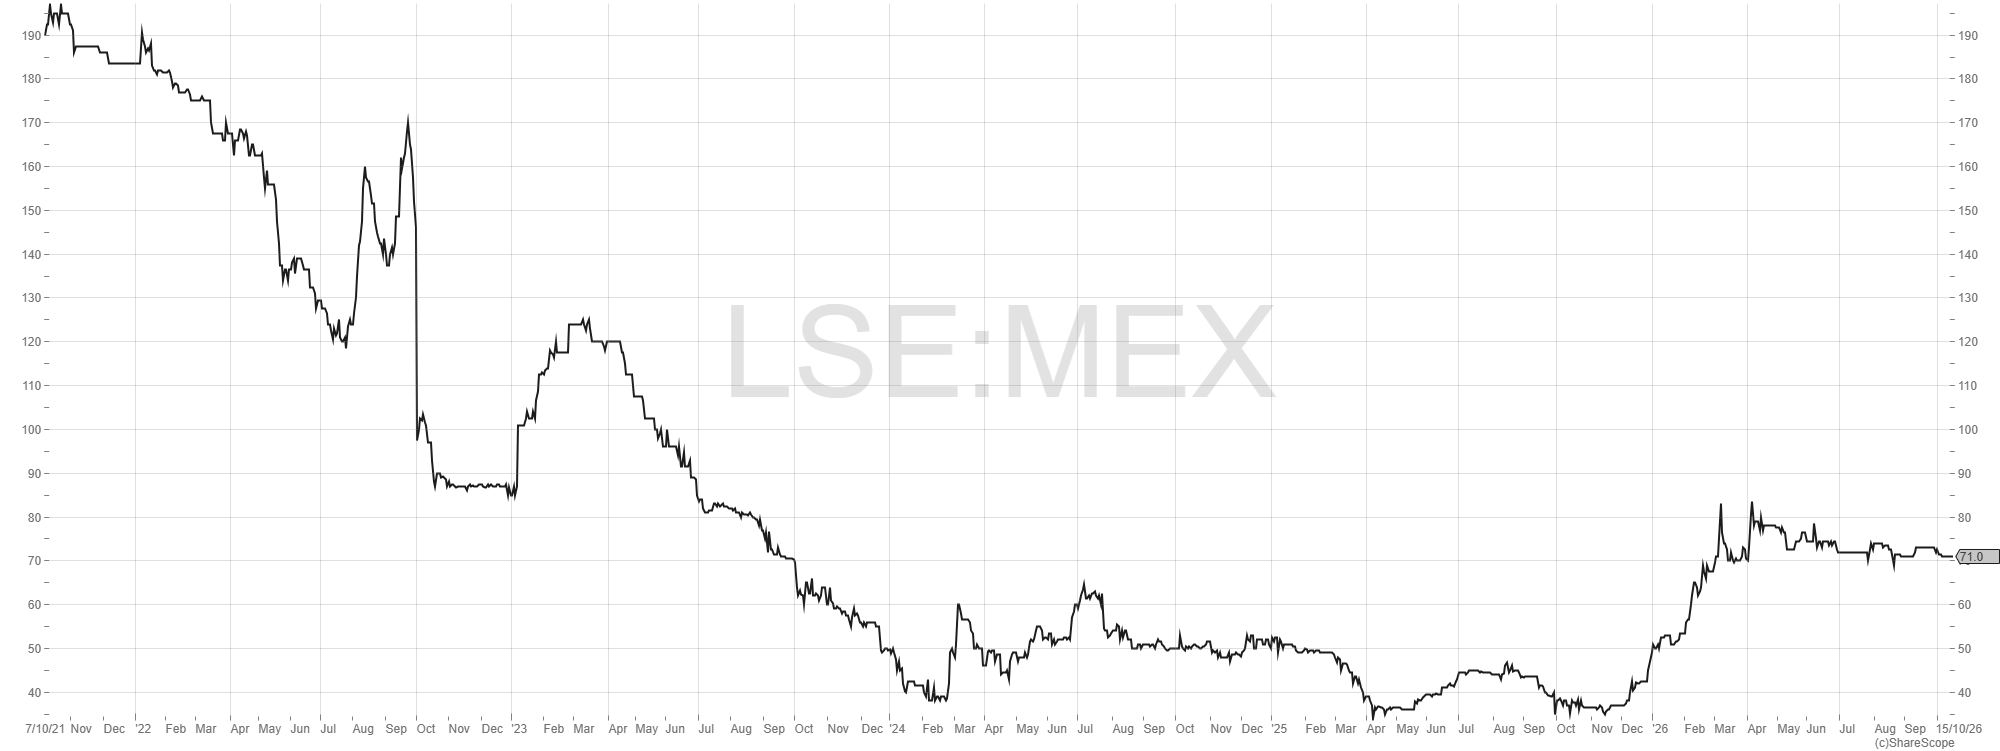
Tortilla Mexican Grill share price performance since IPO
Numbers and strategy
Tortilla Mexican Grill announced its results for the 26 weeks ended 28th June 2026 at the end of September. The numbers looked solid, with total group system sales reaching an all-time high of £100.9 million on a twelve-month trailing basis and group revenue rising by 5.9% to £38.5 million. System sales represent the sum of all sales (excluding VAT) made by both franchised and corporate stores to consumers in the UK, France and the UAE.
While the company made a comprehensive loss for the half of £1.45 million, this was down from £3.7 million in H1 2025. Group adjusted EBITDA (pre-IFRS 16) for H1 2026 was £0.5 million compared to a loss of £0.4 million in H1 2025. EBITDA looks to be a reasonable proxy for cash flow, with the net cash flow from operations for the half being £3.56 million.
There was a difference in contribution between the UK and France businesses, with the UK generating £2.6 million of adjusted EBITDA, but the France operations making an adjusted EBITDA loss of £2.1 million. Action has been taken, with the decision made to close five loss-making Fresh Burritos stores in France, with seven restaurants now trading under the Tortilla brand. It’s worth noting that shares in the company were suspended from trading for around 4 weeks in July. This was caused by a delay in the publication of the annual results, in turn caused by accounting issues in the French operations.
On the balance sheet, group adjusted net debt was £12.4 million at the half-year end, up from £9.9 million 12 months earlier, and drawn against total available facilities of £14.4 million.
The company was positive on the outlook, with UK like-for-like (LFL) sales growth of +19.4% for the 13 weeks to 27th September, with in-store +9.1% and delivery +45.2%. In France, sales growth at the seven converted Tortilla stores has accelerated, with LFLs of +24.4% for the 13 weeks to 27th September, including in-store +19.5% and delivery +88.4%. Total Group system sales reached £102.9 million on a twelve-month trailing basis in August 2026.
Growth initiatives
Some initiatives under the above mentioned Value Creation Plan include UK revenue-driving activities such as broader in-store and delivery menu offerings, corporate menu and catering development, an overhaul of the firm’s loyalty programme and investment in branding. It also includes light-touch restaurant refreshes to the new “Tortilla 2.0” branding, improved restaurant signage, an upgraded kiosk journey and new menu screens, a more focused pricing strategy, and further development of franchise capabilities.
Notably, and buried deep within yesterday’s initial fundraise announcement, was the key line “…management forecasts that implementing these VCP activities could lead to an uplift of at least 10% in FY27 adjusted EBITDA against its base case projections.”
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Tortilla Mexican Grill is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.