

Likewise Group - guidance lifted as sales accelerate in H1 and Q3
Floor coverings business Likewise Group (AIM:LIKE) had a strong first half to the 2026 financial year and now expects the full year numbers to be materially ahead of current market expectations. Despite the bullish update, shares in the company have only edged up by 0.7% to 35p.
The business
Likewise Group was formed in 2018 with the intention of obtaining a meaningful share of the UK flooring distribution market. As of today, the firm is a leading wholesale distributor of floor-coverings, rugs and matting products, serving customers throughout the UK via a number of regionally branded businesses. Growth over the years has been driven by a number of accretive acquisitions of regional wholesale distribution businesses as well as the establishment of new distribution centres and hubs throughout the country. The firm’s main customers are independent flooring retailers and contractors.
Likewise listed on AIM in August 2021, raising £10 million at the time to give it a market cap of £48.1 million. Its current goal is to upscale capacity so it can reach annual sales of £300 million; the previous £200 million target looks set to be achieved this financial year. The company is headed by CEO Tony Brewer, the executive who helped to build UK flooring distributor Headlam into the market leader before co-founding Likewise in 2018. Earlier this month, Headlam announced the intention to appoint administrators, which may open up further opportunities.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Interims ahead and big fundraise since the half year end
For the six months to 30th June 2026 Likewise saw total group revenue increase by 15.4% to £89.9 million. Gross margins improved by 0.8 percentage points to 32.1%, achieved despite a period of raw material pricing pressure and put down to the firm’s focus on pricing, purchasing and product mix.
Significant infrastructure investment made over recent years has created a strong operational gearing, with underlying profit from operations up by 34.4% to £2.25 million and underlying pre-tax profits up by 79.5% to £1.32 million.
There was positive cash generation from operations of £4.11 million in the period, down from £5.2 million in H1 2025 largely due to working capital movements which reflected the higher levels of activity.
Cash and cash equivalents were £3.65 million at the period end, but since then, in July and August, Likewise completed a £32.5 million fundraising. The placing and retail offer elements of the raise were said to be significantly oversubscribed. The company will use the funds to accelerate investment in the business and capitalise on market opportunities, as it heads into its next phase of growth.
Income seekers should be pleased, as Likewise hiked the interim dividend by 20% to 0.165p per share, indicating a total payment of 0.495p for 2026 given the traditional one-third/two-thirds split. At the current share price of 35p that equates to a yield of 1.41%. The firm has a progressive dividend policy, increasing payments broadly in line with earnings.
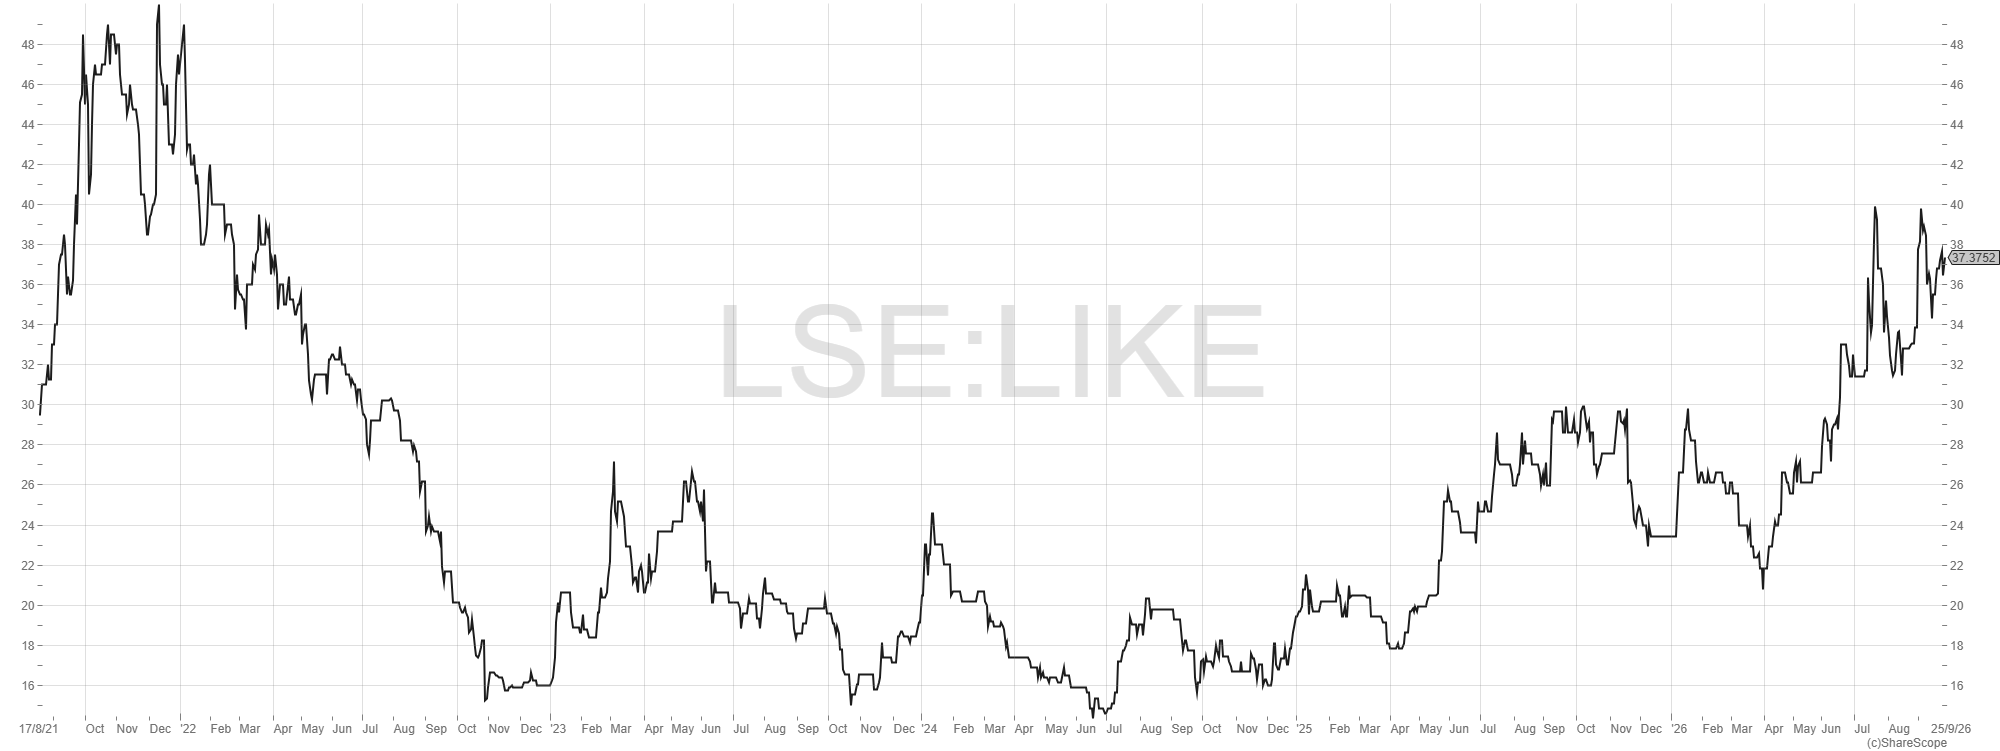
Likewise Group share price chart since IPO
Laying more foundations
In terms of operational highlights, Likewise has been focusing on expanding its logistics infrastructure. As well as a new Leeds Distribution Hub, an extension to its Newport facility progressed as planned in the first half, providing additional distribution and cutting capacity for both the Likewise Wales and Valley operations. By “cutting capacity” the firm is referring to the action of cutting material (not reducing capacity), with cutting operations having commenced here in July. Further cutting capacity has been developed at Derby, with a second cutting shift being recruited for the Autumn.
In addition, in August 2026, Likewise completed the freehold acquisition of a new 60,000 sq. ft. high bay distribution hub in Corby for a total consideration of £9.57 million. This is said to represent a significant further investment in logistics infrastructure and, once operational in January 2027, will materially increase storage, cutting and trunking capacity for the Likewise Floors Logistics Network.
Further, Likewise has recently agreed Heads of Terms for a freehold 47,000 sq. ft. high bay distribution hub in Manchester. The new facility will enable the growth of the A&A Carpets business, and also increase cutting and distribution capacity in the North West for Likewise Floors.
Together with the Leeds investment, the Newport extension and increased cutting capacity at other locations, the Corby and Manchester facilities provide substantial additional headroom for the continued expansion towards the £300 million revenue target.
Outlook
Trading is said to have improved since the half year end, with sales revenue increasing by 29.1% in the period from 1st July to 25th September 2026. Reflecting the strength of trading in the first half and the continued acceleration in the third quarter, Likewise now expects underlying profit before tax for the full year to be materially ahead of current market expectations at not less than £5.0 million, up from £3.1 million in FY2025.
The board remains focused on improving operating margins as volumes increase, allowing the group to generate greater profitability and continue investing in people, infrastructure and service capabilities.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Wickes Group is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.