

Tandem Group - return to profit in H1, shares trade at a deep discount to TNAV
Shares in toys, bikes and golf business Tandem Group plc (AIM: TND) have edged up by 4% to 187.5p on the back of a solid set of results for the six months to 30th June 2026 which show a return to first half profitability.
Tandem is a designer, developer, distributor and retailer of sports, leisure and mobility products. It operates across the four divisions of Toys, Sports and Leisure, Bicycles (including electric), Golf, and Home & Garden.
The firm has a number of exclusive UK licences for its wheeled products including: K-Pop Demon Hunters, Toy Story, Barbie, Hot Wheels, Superman, Peppa Pig, Spiderman and other Marvel Avengers. These are supported by a range of own brands including: Ben Sayers (a 150+ year old golf brand); multiple cycling brands (Dawes, Claud Butler, Falcon and Squish); and various children’s toy brands (Kickmaster for football training; Hedstrom for outdoor play equipment; Stunted for youth scooters; Li-Fe and Wired for e-mobility).
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Results
In the first half, group revenue increased by 6.7% to £11.9 million, delivered amidst mixed trading conditions, with retailers continuing to manage stock cautiously and placing replenishment orders closer to demand.
In the Bikes division, sales increased by 15% year-on-year, with growth strengthening to 24% year on year to the end of August. Own brand electric bikes continued to perform strongly, with sales increasing by 36% year on year, both in H1 and for the year to August.
Home & Garden continued to perform strongly, up 76% year on year, and to August increasing by 52% year on year. A second consecutive summer of exceptionally high temperatures supported significant demand for cooling products, while extended periods of warm and sunny weather also benefited outdoor categories including awnings, pergolas and parasols.
Trading in Toys, Sports & Leisure was more challenging, with outdoor toy sales 13% below the prior year, a position which remained unchanged for the year to the end of August. Tandem continues to invest in product innovation and the development of its licensed portfolio, with over 50 new products launched during H1.
The Golf business also had a challenging period, with revenue 19.2% below the prior year in H1, improving to 10% below for the year to the end of August. This reflected the timing of certain orders compared to the previous period.
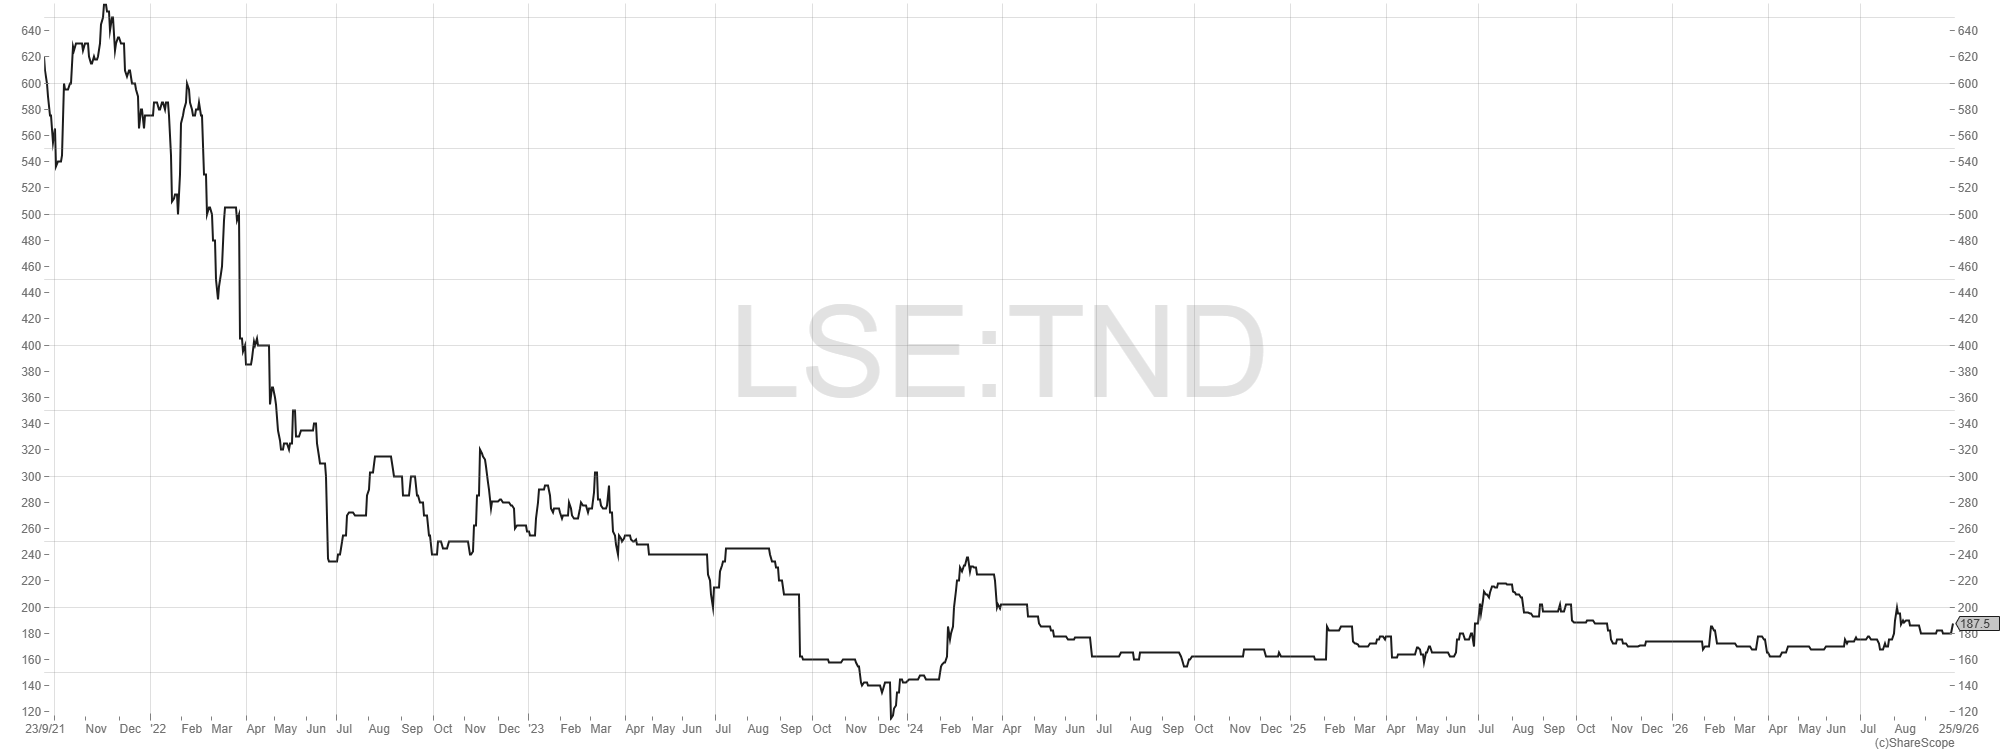
Tandem Group 5-year share price chart
Profits helped by higher gross margins
To profits, and gross profit grew by 15% to £4.0 million, with the gross margin increasing to 33.3% from 30.9% in H1 2025. This was mainly due to new products, categories and currency fluctuations. Despite operating expenses rising from £3.5 million to £3.7 million, Tandem managed to grow adjusted EBITDA from £81,000 to £374,000. Pre-tax profits were £70,000 against an H1 2025 loss of £378,000.
On the balance sheet, net debt at the period end reduced to £2.8 million from £3.2 million 12 months previously but up from £1.9 million at the year end in December (like many retailers, Tandem’s numbers are weighted to the second half due to the important Christmas trading period).
Notably, net assets were £26.1 million at the period end, up from £23.3 million 12 months previously and flat compared to the December year end. Tandem’s current market cap is £10.3 million, meaning that the shares currently trade at a 60% discount to NAV. The core assets relate to property, plant and equipment (£16.5 million - which is mostly freehold property), £6.5 million of inventory and £6.5 million of receivables. If we strip out £5.4 million of intangibles, Tandem is trading at around 0.5 times tangible NAV.
Outlook
On the outlook Tandem said that trading since the end of the first half has remained encouraging, with revenue for the year to the end of August up by 9.1% year on year. It flagged continued economic uncertainty as it enters its traditionally stronger second half period but is encouraged by a broader product portfolio, improved margins and continued growth across a number of its key categories and channels. Tandem remains confident of delivering a full-year result in line with current market expectations, and if it does it intends to declare a dividend for the full year. For FY2025 the dividend was reinstated at 3p per share, which at the current share price of 187.5p equates to a modest yield of 1.6%.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Wickes Group is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.