

Wickes Group - volume-led H1 keeps FY2026 on track, shares up 8%
Shares in home improvement retailer Wickes Group (LSE:WIX) have added 14.8p, rising by 8.4% to 191.4p, after the firm released a decent set of numbers for the 26 weeks to 27th June 2026.
The Business
Wickes is one of the largest home improvement retailers in the UK. The business operates from a network of 229 stores, which support nationwide fulfilment, and through digital channels including: its website, TradePro mobile app for trade members, and Wickes DIY app. Wickes has a balanced business focusing on three key customer journeys - TradePro, DIY (together reported as Retail), and the project-based Design & Installation division, which comprises sales of products and services which can be designed and/or installed, such as kitchens, bathrooms and solar. The firm has had its own market listing since April 2021 when it completed a demerger from builders’ merchant Travis Perkins.
Interims
Total revenue for the period was £865.3 million, up 2.1% year-on-year but only up by 0.7% on a like-for-like basis (like-for-like measures the equivalent times in both periods being compared, with last year’s H1 covering slightly different dates, and also adjusts for store closures and openings).
Across the two divisions, the larger Retail business grew sales by a modest 0.8% to £639.8 million but they were down by 0.3% like-for-like, characterised by very wet weather conditions in Q1 and a partial recovery in Q2. DIY sales were said to be broadly flat but with gains in decorative, gardening and timber helping to boost market share. A stronger performance came from the TradePro business which grew sales 5% year-on-year, as local trade professionals continue to choose Wickes to save them time and money. Sales were also driven by an increase in active members to 671,000, up from 615,000 at the end of H1 2025.
Meanwhile, in Design & Installation revenues rose by 5.7% to £225.5 million, with a 3.6% like-for-like gain. Delivered sales have now been in positive growth for five consecutive quarters. The overall number of D&I projects has increased, however ordered sales by value for the period were slightly lower than in the same period last year. Lifestyle Kitchens and Bespoke Bathrooms continue to generate strong ordered sales growth but with customers being more considered for larger purchases, the Wickes Bespoke Kitchen ranges are seeing slower orders.
To profits, and adjusted profit before tax grew slightly, by 1.1% year-on-year to £27.6 million, with productivity actions partially mitigating cost inflation.
On the balance sheet, net cash was £151.6 million at the period end, with that figure covering 36% of the current £420.4 million market cap. Net cash was down from £158 million at the end of the first half last year, reflecting growth investments, £26.3 million being returned to shareholders (£16.3 million of dividends + £10 million share buybacks), plus £9.2 million of net funding for employee benefit trust share purchases. Cash was also spent on eight refits/refreshes of stores.
More money will be returned to shareholders, with the interim dividend increased by 2.8% year-on-year to 3.7p per share. On last year’s total payment of 10.9p, the shares yield 5.69% on a historic basis.
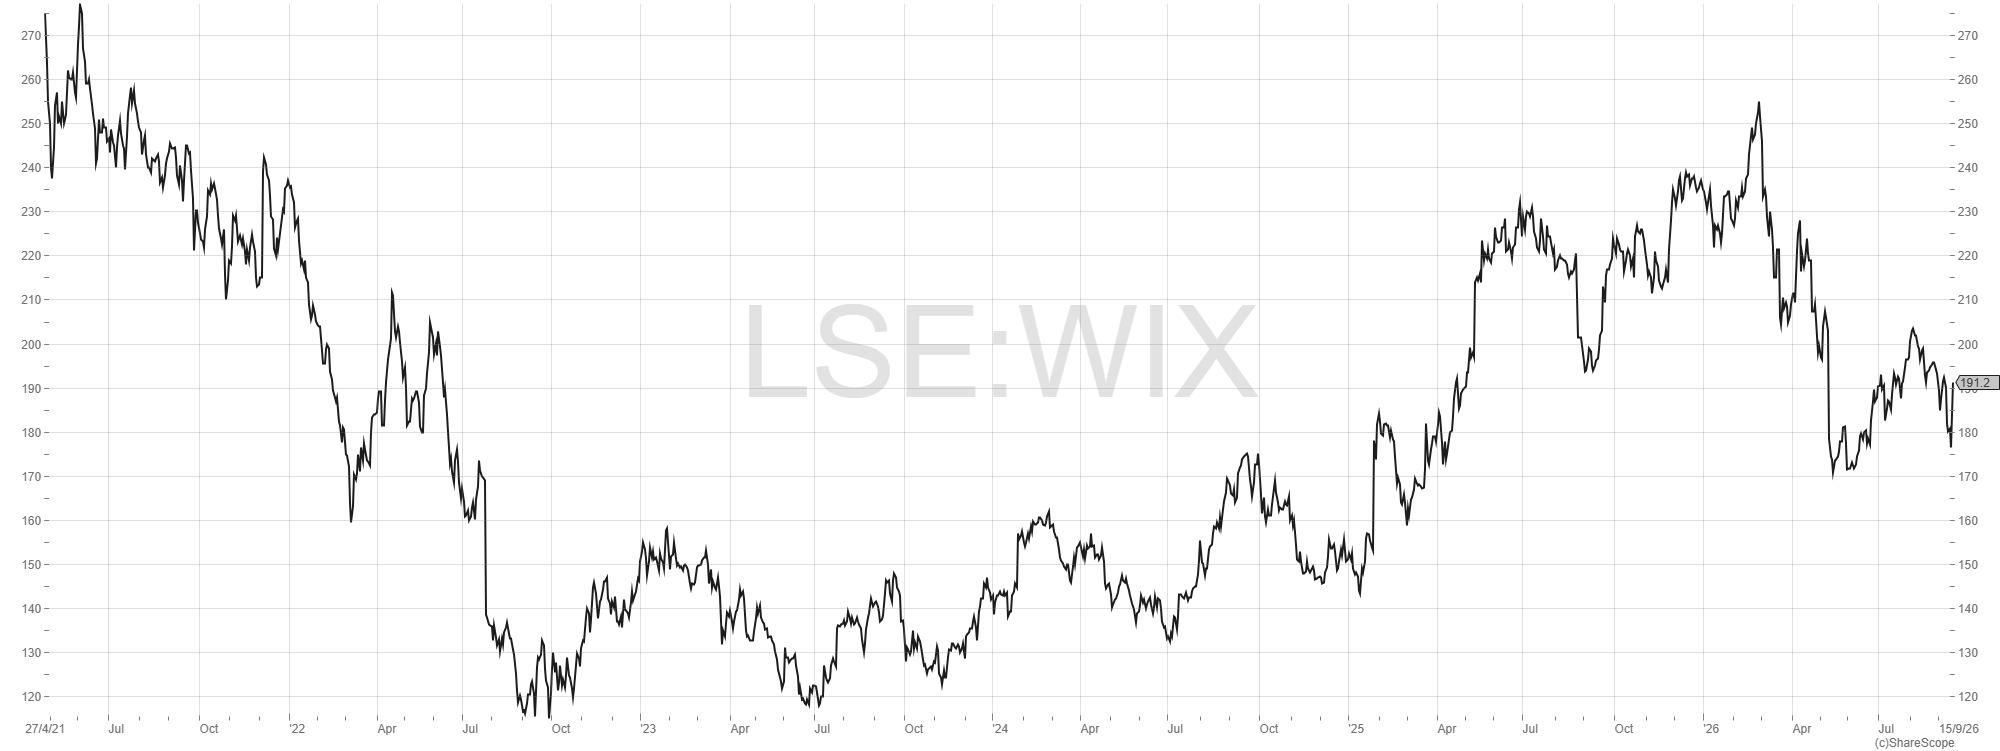
Wickes Group share price since IPO
Outlook
On the outlook, Wickes confirmed that, whilst the consumer environment remains uncertain, the firm is on track to meet consensus expectations for 10% growth in adjusted PBT for FY2026. As at 2nd September 2026, consensus compiled from all covering analysts is for adjusted PBT in 2026 of £54.6 million, with a range of £52.8 million to £56 million.
Trading in Q3 so far is said to have shown a significantly improved trend, with a step up in Retail to mid-single-digit LFL revenue growth.
In the second half investors can expect 4-5 store openings, as the firm progresses its ambition to reach 300 stores. Wickes is also doing its bit for crime reduction, with a campaign to tackle tool theft. It will offer free marking to protect over 260,000 tools, reinforcing its position as a trusted partner for tradespeople.
Investors can look forward to a more detailed Q3 trading update in late October.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Wickes Group is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.