

Touchstar - transformation on track, but market wary as recovery waits for 2027
Shares in technology firm Touchstar (AIM: TST) have fallen by 9% to 77.5p despite the firm announcing in an H1 trading update that it expects annual losses to be lower than market expectations. However, the firm did remain cautious on its outlook.
The Business
Touchstar describes itself as a provider of connected technology solutions that help organisations in a variety of industry sectors secure and manage the logistics of people and product. The firm designs and builds rugged mobile computing devices and develops software solutions used in a wide variety of field-based delivery, logistics and service applications. Some product examples include: proof of delivery solutions, access controls systems, commercial fire alarm systems and employee time & attendance systems.
Touchstar’s strategy is to deliver sustainable long‑term growth through a combination of product innovation, market expansion, operational efficiency and disciplined investment. Last year the firm began a comprehensive restructuring of its business which amongst other things included: appointing long-standing subsidiary managing director Lynden Jones as CEO, streamlining production processes to improve efficiency, migrating software development roles from India to Manchester, and restructuring the sales team to improve customer engagement and enable cross-selling. In addition, Touchstar said it would be analysing acquisition targets to accelerate growth.
H1 Trading
The H1 update revealed that revenues for the period were flat at £3.4 million, with Annual Recurring Revenue (ARR) of £1.6 million up by 4.6%. While gross margins slipped from 48% in H1 2025 to 46%, an adjusted EBITDA of £0.03 million was made in the period, a turnaround from H1 2025’s loss of £0.24 million. However, pre-tax losses were flat at £0.1 million.
On a more positive note, the order book at the end of June stood at £2.63 million, with order intake for the half up by £739,000 compared to H1 last year. Also, cash remains strong, with cash net of overdraft at the period end standing at £2 million, although down from £2.34 million at the year-end in December. With a current valuation of £6.1 million, that means net cash covers around a third of Touchstar’s market cap.
Strategy
Touchstar also highlighted five areas of operational and strategic capability it progressed during the first half.
• Product focus: the decision to cease further standalone development and marketing of electronic proof of delivery software PODStar simplifies the logistics portfolio, concentrates future investment and provides a clearer basis for strengthening Touchstar's existing logistics capabilities.
• Engineering leadership: securing a Head of Engineering appointment strengthens roadmap ownership, accountability and the firm’s ability to modernise products and creates capacity to improve delivery.
• Commercial resilience: the internal sales model has been redesigned to improve customer coverage and service, strengthen cross-selling and reduce reliance on individual account managers.
• Customer engagement: customer enquiry and quotation processes are being restructured to improve responsiveness, technical accuracy and future scalability.
• Decision discipline: clearer priorities are enabling faster decisions and more disciplined allocation of resources.
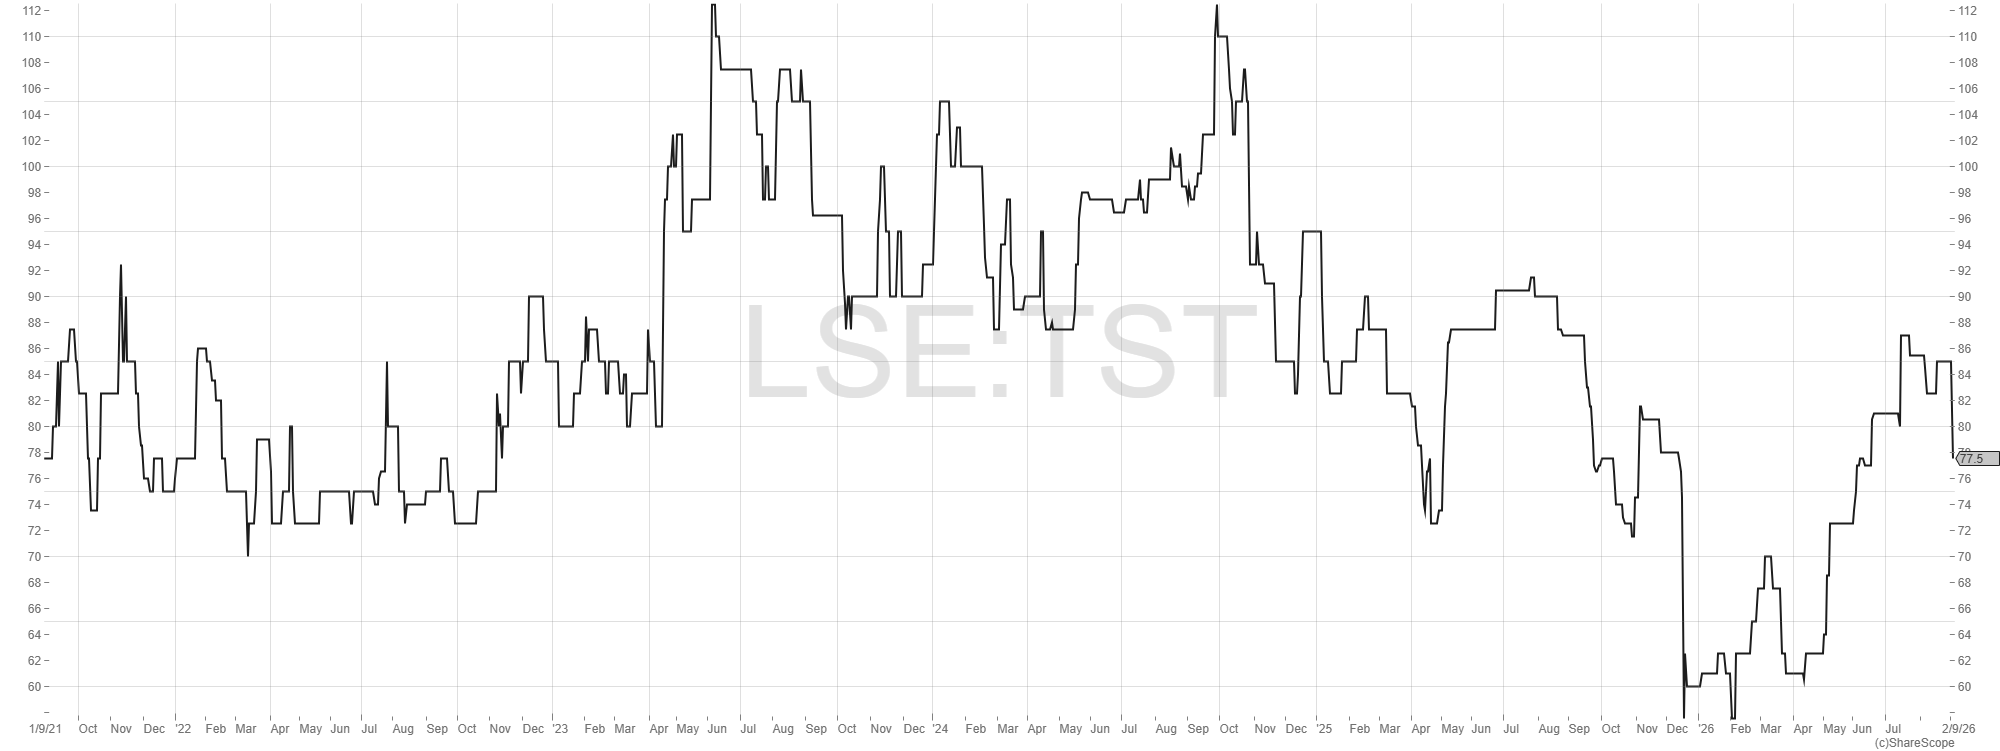
Touchstar 5-year share price performance
Outlook
On the outlook, Touchstar was cautious regarding the timing with which current opportunities will convert into orders, with customer decision-making and the timing of orders continuing to be influenced by the wider economic environment. As a result, revenues in H2 are expected to be slightly weaker than in the first half. However, as noted above, losses are forecast to be lower than the market expects.
Further, Lynden Jones, summarised: “We remain on track for our expectation of a return to profitability in 2027." Other key comments from the CEO included: “I am pleased with our progress in H1 as we continue the transformation started in H2 2025 and expect further progress in H2. We remain firmly on track with our strategic objective to rationalise the business, strengthen its operational foundations and create a platform capable of delivering sustainable revenue growth.”
Notably, Jones has been regularly buying shares in the company recently. Over the past three months he has spent around £97,000 in four separate transactions, taking his stake to 6.4% of the business.
Investors will now be looking out for further updates in the interim results, which should be published this month if last year’s release timeline is used as a guide. Of interest will be the company’s decision on the interim dividend, which may look under threat given the caution on trading. For the full 2025 financial year the firm increased the payment by 8.3% to 3.25p per share, despite adjusted net profits falling by 25.8% to £312,000. If maintained for the full year that equates to a yield of 4.19% at the current share price.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Touchstar is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.