

Neuroscience imaging and biomarker analytics business IXICO plc (AIM: IXI) has continued its recent run of good news by announcing the winning of a global Phase 3 clinical trial contract in Huntington’s disease (HD) with an international biotechnology company. The contract is worth £2.7 million in revenues to IXICO over the next six years.
This is the second Phase 3 HD contract that IXICO has been awarded over the past 12 months, which the company says reinforces its position as a trusted partner to biopharma companies as an increasing number of innovative new therapies in HD advance to late stage clinical trials and potential FDA approval.
This follows news on 22nd October that the firm has won two contracts, the first with a biotechnology company to manage and analyse neuroimaging for a Phase 2b clinical trial in Alzheimer’s disease, and the second a contract extension with an existing large international life sciences and diagnostics client to support the validation and regulatory approval for a blood-based biomarker being developed to diagnose Alzheimer’s disease.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
The business
IXICO is a global leader in neuroscience imaging and biomarker analytics, using its proprietary AI-driven platform to help advance the treatment of neurological disorders and reduce the uncertainties associated with drug discovery, development and monitoring. As a key part of the global neurological disease research community, the company has built a global reputation and 20-year track record as an end-to-end Imaging Contract Research Organisation (iCRO) working with leading pharma companies, innovative biotechs, disease consortia and non-profit organisations. IXICO has supported hundreds of neurological clinical trials, analysed hundreds of thousands of scans and built an expansive network of expert imaging centres around the world.
The IXICO Platform is tailor-made for neurological disease, reliably processing data from global trials, precisely measuring key imaging biomarkers associated with the identification, progression and treatment of diseases such as Alzheimer’s, Huntington’s and Parkinson’s. Image data is interrogated by the Platform and IXICO’s expert scientists translating complex data into clinically meaningful insights while minimising data variability and increasing reproducibility.
IXICO’s growth is driven by momentum in the neuroscience market, increasing demand for its specialist neuroimaging and biomarker analytics capabilities, and the execution of its Innovate, Lead, Scale strategy, maximising its ability to capture the market opportunity. The firm continues to secure new clinical trial programmes, expand relationships with existing customers and diversify its revenues across neurological diseases, clinical trial phases and customer types.
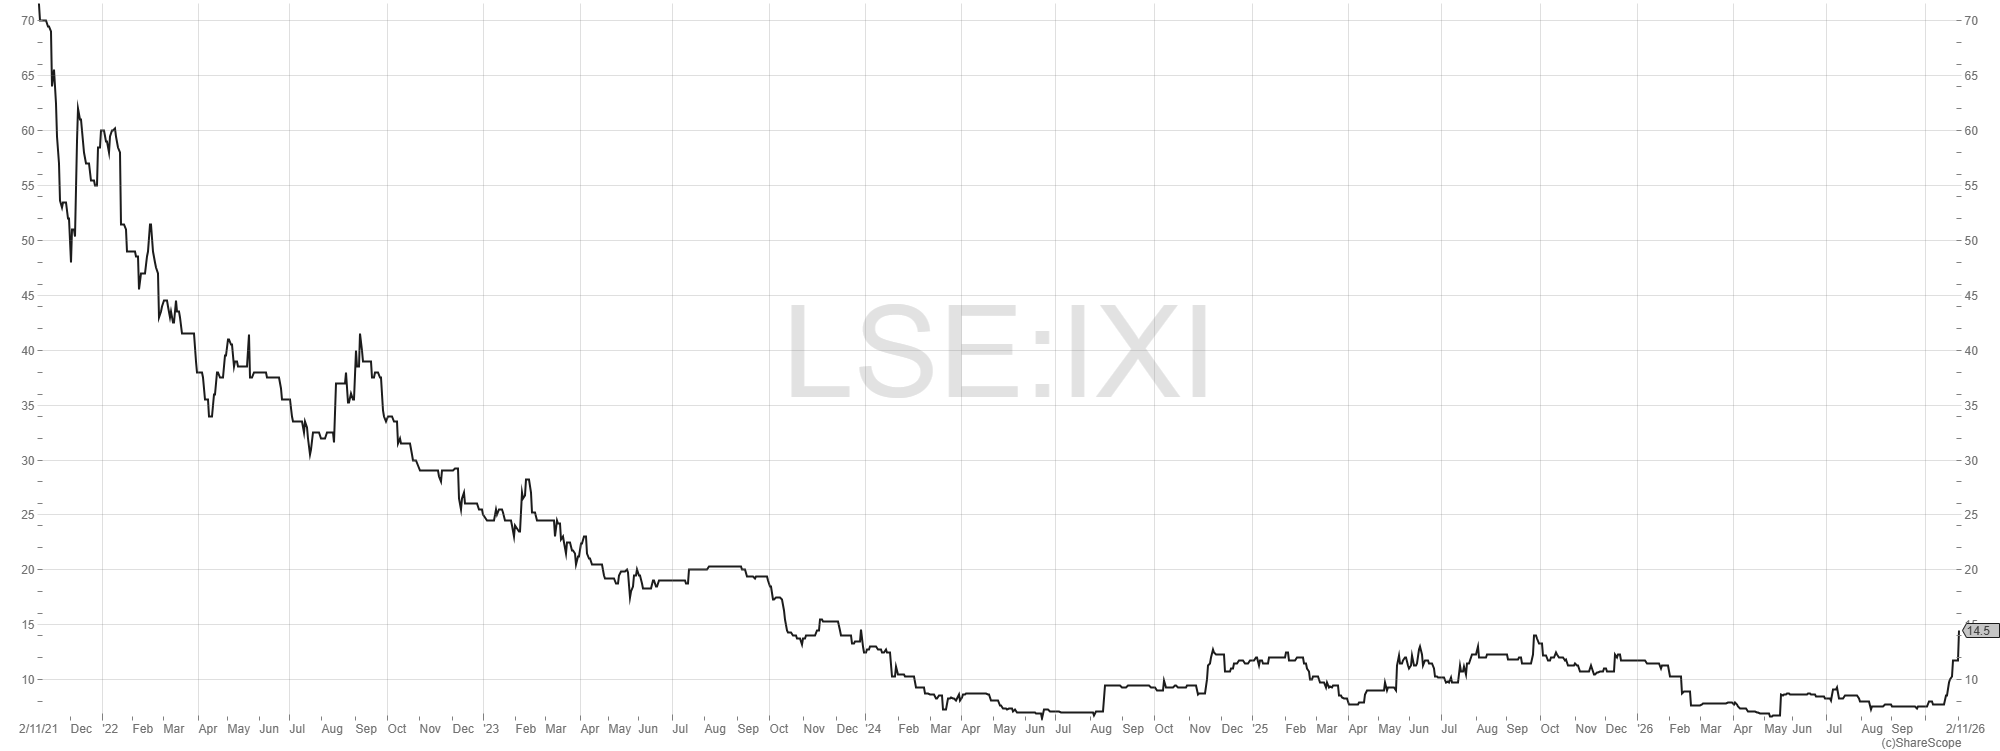
IXICO 5 year share price chart
Positive trading
The recent contract news follows a positive trading update made by IXICO on 20th October, in which it reported that FY2026 revenue (to end September) is expected to be £8.3 million, up from £6.5 million in FY2025. This additional growth exceeds upgraded revenue guidance made in July this year (which moved revenue expectations from £7.5 million to £8.0 million), after an acceleration in analysis orders during the final quarter.
IXICO ended the year with cash of £10.4 million, up from £3.5 million a year earlier, reflecting a £9.4 million net capital raise completed in April this year. While IXICO is increasing investment for growth, the revenue performance is expected to drive improved EBITDA versus existing guidance of a £1.7 million loss. The full year results will be announced in December.
Comment
It’s been a good few weeks for IXICO, with both annual revenues and the year-end order book being the highest since FY2022, the last year it made a profit. Today’s win further strengthens that book, with the increasing scale being highly encouraging for a move back into profits. IXICO has high gross margins (up to 53% in H1 2026 from 50% in H1 2025) and a strong operational gearing.
We note the progress being made in the area of Alzheimer’s disease, where IXICO is well placed for further growth. According to the results of a study published in May this year, Alzheimer’s Disease Drug Development Pipeline: 2026¹, compared to a decade ago, there are substantially more drugs (+35%) being tested for Alzheimer’s disease in more clinical trials (+40%) targeting a greater number of aspects of the disease. Analysing trials registered on clinicaltrials.gov, the researchers found there are 158 drugs for the treatment of Alzheimer's disease in the 2026 drug development pipeline, with 55,000 participants required to populate all currently active trials.
In Huntington’s disease, there are currently 44 interventional clinical trials listed on ClinicalTrials.gov, up from 30 in February 2025. The industry has recently seen Skyhawk Therapeutics initiate a phase 2/3 programme of HD therapy SKY-0515. Elsewhere, Novartis Pharmaceuticals has initiated the phase 3 INVEST-HD study of votoplam (PTC518). This comes after Novratis licensed the therapy from PTC Therapeutics in an agreement which saw PTC receive an upfront payment of $1 billion, with up to $1.9 billion in development, regulatory and sales milestones, a profit share in the U.S., and double-digit tiered royalties on ex-U.S. sales.
Cash covers round a third of IXICO’s current £31.8 million market cap, with no bank debt on the balance sheet as at the last reported date of 31st March 2026, providing the company with a significant runway to return to profitability.
¹Cummings JL, Zhou Y, Yang Y, et al. Alzheimer's disease drug development pipeline: 2026. Alzheimer's Dement. 2026; 12:e70251. https://doi.org/10.1002/trc2.70251
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
IXICO is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.