

Victorian Plumbing Group - revenue up 11% to £344m with profits (slightly) ahead of expectations
Bathroom retailer Victorian Plumbing Group (AIM: VIC) has announced that strong momentum has continued throughout the second half of FY2026 (to end September) with record revenue, further market share gains and adjusted PBT ahead of market expectations (but not by much).
The business
Victorian Plumbing describes itself as the UK's leading bathroom retailer, offering an unrivalled high-quality product range and excellent stock availability to B2C and trade customers. The company offers its customers a one-stop shop solution for the entire bathroom with own and third party brands across a wide spectrum of price points. The business also includes MFI, an online-only UK retailer launched in 2025, offering a growing range of stylish furniture and homewares.
Headquartered in the North West, Victorian Plumbing and MFI employ staff across several locations in the UK. Earlier this year the company bought Sovereign Transport Services, a transportation services business based in Merseyside, providing haulage services to the group and to a small number of other goods-based businesses in the North of England. The company is also a sponsor of football team Bristol City, with The Robins wearing the company’s logo on the front of their shirts for the 2026/27 and 2027/28 seasons.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Trading
Group revenue increased by c.11% to c.£344 million in FY2026, outperforming the wider repair, maintenance & improvement market. This market declined by 1.7% according to the Barclays UK Consumer Spend Report for Home Improvements & DIY, covering October 2025 to August 2026. Growth was primarily driven by a c.13% increase in total orders, offset by a c.5% reduction in average order value. Victoria also benefited from c.£7 million of revenue generated by Sovereign Transport Services, and c.£3 million of revenue from MFI. Tiles and flooring revenue grew by c.76%, to c.£31 million, and trade revenue grew by c.6%, to c.£78 million.
Group adjusted PBT is expected to be c.£0.3 million ahead of market expectations at c.£22 million. This comprised c.£26 million profit at Victorian Plumbing (FY2025: £24.3 million profit) and a c.£4 million loss at MFI (FY2025: £2.5 million loss), as the firm continues to invest in establishing MFI in the UK homewares market. Group year-end cash remained strong at c.£25 million (FY2025: £17.7 million) with continued healthy operating cash conversion.
Before this update the analyst consensus for the year was for £328.4 million of revenue (compared to £310 million in 2025) and £21.7 million of adjusted PBT (£21.8 million in 2025).
Investors will get more information on 8th December 2026 when the full year results are released.
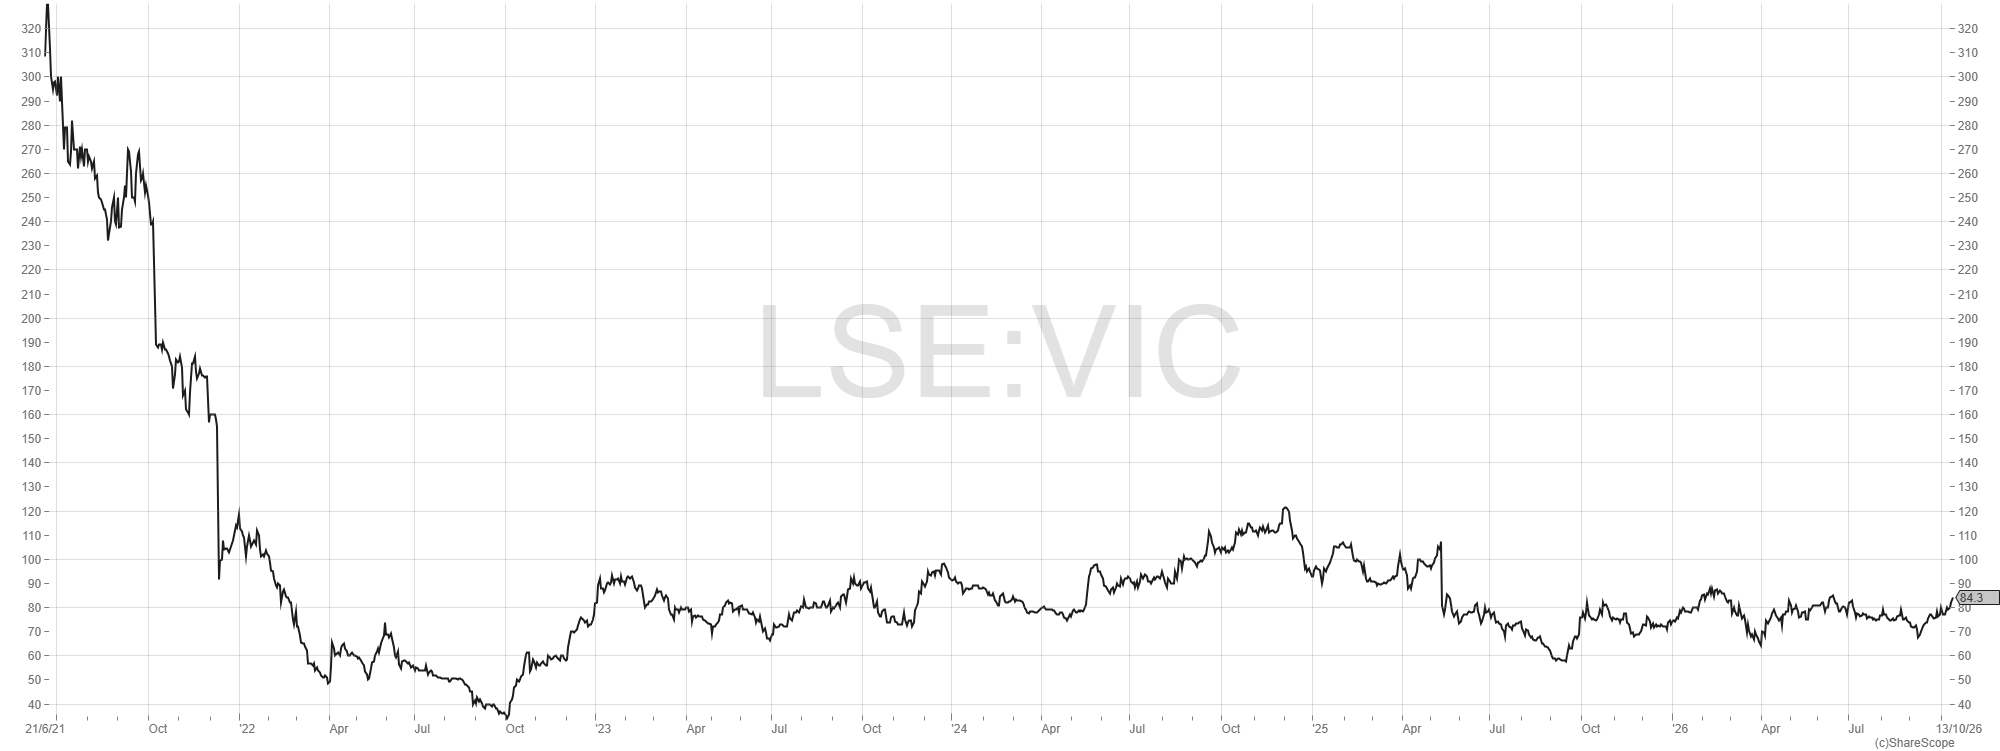
Victorian Plumbing share price performance since AIM IPO
Comment
A good performance from Victorian Plumbing, although investors might be concerned about margin slippage. The adjusted PBT margin for the year is 6.4% on today’s figures, up from 5.6% at the interim stage but down from 7% in FY2025 and 8% in FY2024. Recent reasons given for falling margins include planned investment in MFI and a full six months of expense in H1 2026 vs. just three months in H1 2025 associated with a 20-year lease on a new distribution centre. Investors will be looking for an improvement as the MFI business hopefully moves into profitability.
For FY2025 the firm paid a total dividend of 2.15p, up 34%, and increased the FY2026 interim payment by 5.7% to 0.74p per share. Assuming a similar increase for the full year, the dividend yield is 2.7%.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Victorian Plumbing is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.