

tinyBuild - shares slip despite FY numbers expected to be ahead of expectations
Shares in video games developer tinyBuild (AIM: TBLD) have fallen by 5.8% to 14.125p despite the firm posting a strong set of results for H1 2026 and announcing that full year results are on track to be ahead of expectations.
The business
Founded in 2013, tinyBuild is a leading premium AA-rated and indie video games publisher and developer. The company has a strong portfolio of over 90 titles and it strategically secures access to IP and partners with developers to establish a stable platform on which to build multi-game and multimedia franchises. Some of its titles include: Probably Stolen, a cyberpunk shopkeeping simulator set in a dystopian space station; Last Harbor, a zombie apocalypse set on a boat; and the long-running horror series Hello Neighbor.
Headquartered in Bellevue, Washington, USA, the company has key operations worldwide, with employees, contractors or partners in multiple locations across five continents. The medium-term strategy is to expand its position as a leading global video games developer and publisher, focussing on IP ownership while creating long-term scalable franchises across multiple media formats.
tinyBuild listed on AIM in March 2021, raising £36 million for a market cap of £154.4 million. However, the current market cap is £55.6 million. In the past few years the firm has been affected by the wider challenging conditions in the video game industry. It had a particularly tough time in 2023 when it posted an operating loss of $63.8 million as a result of $48.1 million of impairment charges, and a $3.5 million one-off legal settlement alongside lower revenues and higher costs. However, the firm seems to be bouncing back, with FY2025 results ahead of expectations and today’s H1 numbers being solid.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Financial highlights from H1
For the six months to 30th June 2026 tinyBuild managed to grow revenues by 18% to $20 million following a strong catalogue performance and new launches. Its smaller events business again showed good growth, with sales up by $0.1 million to $0.9 million. The contribution from own-IP (first and second party) titles was stable at 85% of Gaming segment revenues with a higher weight of second party titles. Back catalogue sales, titles released prior to the current fiscal year, dropped to 68% of Gaming revenue thanks to the success of new releases such as Hozy, ALL WILL FALL and SAND. There was an expansion of catalogue IP, including the console launch of I Am Future, the first DLC for The King is Watching and Nintendo Switch launch for Kill It With Fire 2.
Profits were down however, with gross profit of $9.8 million comparing to $10.4 million in H1 2025, reflecting higher royalty payments due to the success of second party new releases. Adjusted EBITDA was down by $1 million to $3.2 million, also reflecting higher spend on marketing for new launches.
On the balance sheet, cash and cash equivalents were broadly unchanged at $4.7 million at the period end. Net cash from operating activities was down slightly at $6.4 million (H1 2025: $6.8m), including a modest increase in software development costs to $6.4 million (H1 2025: $6.2m).
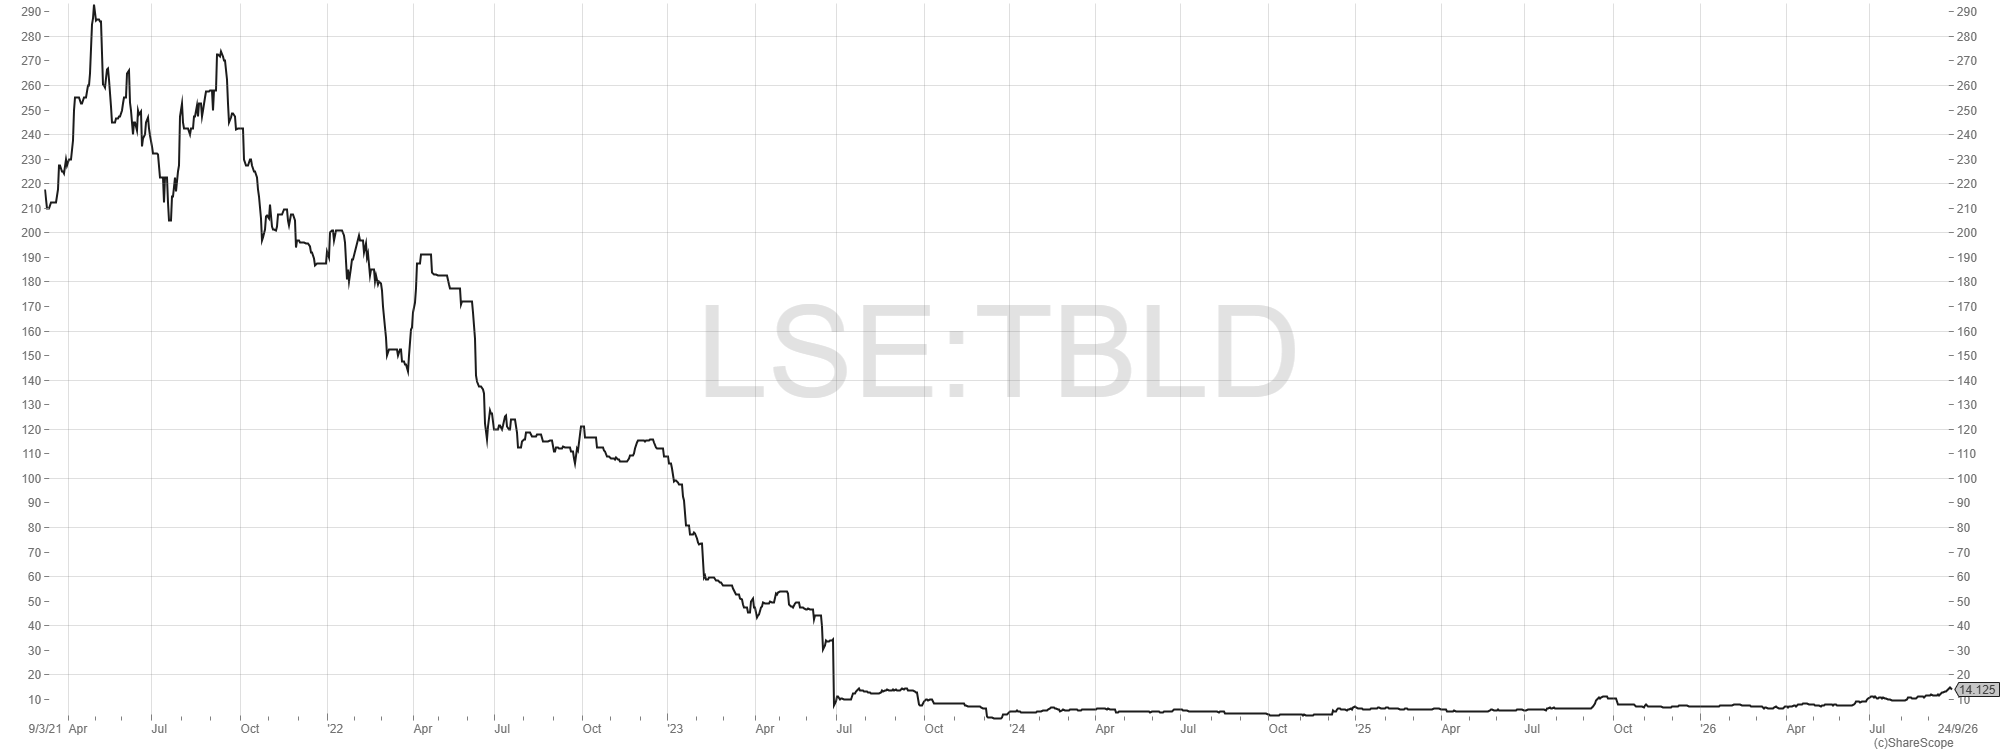
tinyBuild share price since IPO
Second half trading and outlook
In the second half we will be looking out for more news on newly announced games including Graveyard Keeper 2 and Last Harbor, plus numerous playtests and demos, including ReStory, Hull Rupture, SpeedRunners 2 and The Lift. Since the half-year end, new titles have been released including Happy’s Humble Burger Cult and ReStory, plus The King is Watching on console, with the announcement of a new game, Probably Stolen.
tinyBuild commented that 2026 started with a strong revenue performance, though much uncertainty remains about the second part of the year in a crowded market. However, the pipeline is said to be strong and includes a number of larger-budget ($5 million+), high-potential new IPs alongside the continuous expansion of catalogue titles.
The company flagged that ongoing geopolitical and macroeconomic risks are making it cautious. But all considered, the Board remains confident the company is on track to deliver full year results ahead of expectations. Despite today’s share price fall, tinyBuild shares have more than doubled so far in 2026, up from 7p at the start of the year.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
tinyBuild is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.