

Synectics - EBITDA guided to top of range as shares jump 11.6%
Shares in Synectics (AIM: SNX) have risen by 11.6% to 192.5p after the security, surveillance and operational intelligence firm announced a positive trading update for the year ending 30th November 2026. Revenue for FY2026 is now expected to be in line with current market expectations, with adjusted EBITDA at the top end of the previously communicated range of £3.7 million to £4.1 million. However, that’s still down on FY2025 adjusted EBITDA of £8.5 million and FY2024’s figure of £6.3 million.
The business
Synectics is a leader in advanced security and surveillance solutions that help protect people, property and assets around the world. It operates via two divisions.
Synectic Systems develops and delivers its proprietary, technology-led solutions to specialist markets globally, including oil & gas, gaming, transport, critical infrastructure, and public space, through local systems integrators and channel partners. Capabilities centre around a proprietary software platform, Synergy, that is tailored to the unique requirements of each client, and specialist hardware for oil & gas markets.
Ocular delivers integrated solutions, service, and support directly to end-users in the UK and Ireland, principally within public space, transport, and national infrastructure, utilising a combination of proprietary technology and third-party products.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
Trading update
In its trading update, Synectics said that the expected FY2026 outcome reflected stronger margins and good performance across the group, demonstrating the resilience of a diversified business and the early benefits of changes being implemented under the group’s ‘5P’ strategy. Changes include simplifying product deployment, strengthening partner strategic account management, and improving processes and commercial discipline across the business. The 5P strategy was launched at the start of the year with a view to transforming Synectics into a scalable, product- and partner-led business and significantly expanding its share of a serviceable market which it estimates to be worth c.£2 billion.
As highlighted in the interim results in August, there was uncertainty around the timing and conversion of Energy market opportunities, particularly in the Middle East. These opportunities are said to remain active and are expected to extend into FY2027, with the group continuing to hold a significant pipeline in the sector and encouraging signs of progression.
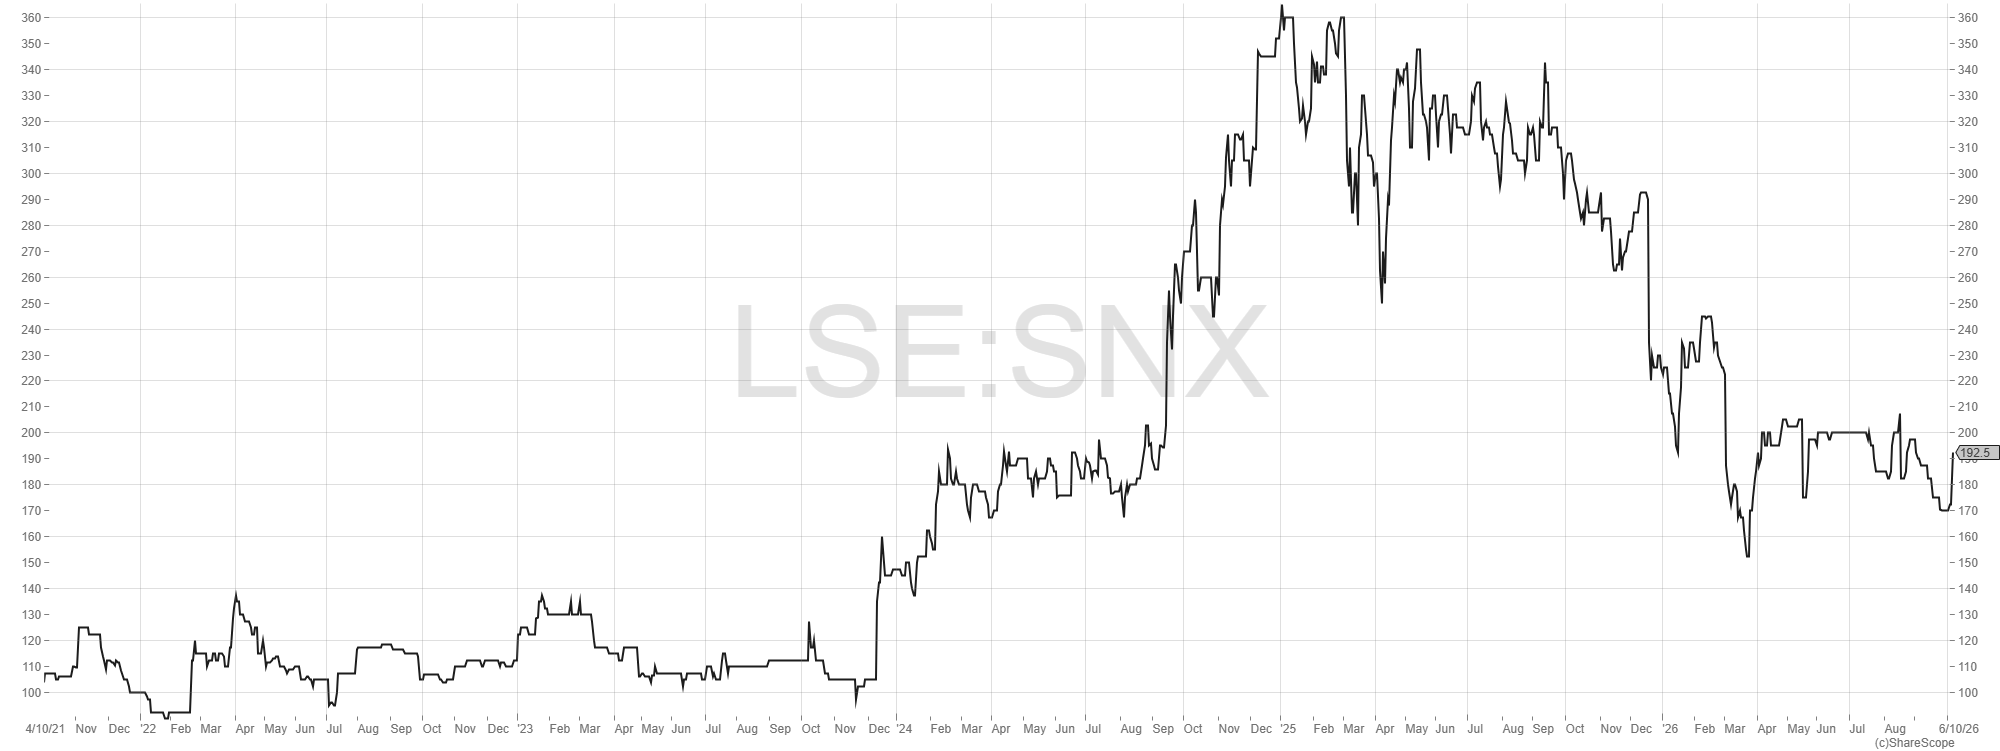
Synectics 5-year share price chart
Recent contract wins show progress after a tough first half
The update comes on the back of two recently announced contract wins.
At the beginning of September, Synectics announced that subsidiary Ocular Integration had secured contracts with an aggregate value of £1.4 million to provide on-vehicle surveillance technology for 220 new buses being introduced by a UK regional authority. This followed an announcement in late August that Synectics had secured a £1.4 million contract to provide an integrated security and surveillance solution to global energy company Eni for its Kutei Floating Production, Storage and Offloading Project in Southeast Asia.
The first half was challenging for Synectics, the business posting revenues of £22.2 million, down from £35.5 million in H1 2025. This was expected, however, coming after significant revenues from a non-repeating gaming contract of £7.8 million were earned in H1 2025. There were also additional delays to expected Energy revenues due to the conflict in the Middle East. Adjusted EBITDA for the period was £1.0 million, down from £4.2 million 12 months previously. The balance sheet was strong, however, with net cash as at 31st May standing at £10.5 million against a current market cap of £32.7 million. The company also maintained its interim dividend at 2.2p per share. If last year’s total payment of 5p is maintained, the shares will yield a modest 2.6%.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Synectics is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.