

Concrete placing equipment manufacturer Somero Enterprises (AIM: SOM) expects its performance for the full year to 31st December 2026 to be modestly ahead of previous expectations. Following continued positive trading since the interim results were released in September, the company now expects annual revenue of c.US$100 million (US$95 million previously) and adjusted EBITDA of c.US$20.5 million (US$19.5 million previously).
Activity is said to have been supported in part by AI-related data-centre construction in the US, alongside stabilisation in other private, non-residential construction markets. Customers continue to report healthy levels of activity and good visibility of work into 2027.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
The business
Somero Enterprises manufactures laser-guided and technologically innovative machinery used in horizontal concrete placement, to advance the productivity, concrete flatness and efficiency of the job site. Somero equipment has been specified for use in the construction of warehouses, manufacturing assembly plants, exterior paving and parking structures, retail centres, and other commercial construction projects that require extremely flat concrete slab floors. The firm operates in markets across the globe, selling products in more than 90 countries, working with small, medium and large concrete contractors and self-performing general contractors. Its equipment has been used in construction projects for a wide array of the world’s largest organisations.
Outlook
The backlog for November and December is said to remain robust, giving Somero confidence in the outcome for the year. However, the company remains mindful of continued market uncertainty, with tariffs, elevated interest rates and immigration policy still weighing on the industry, coupled with recent changes to the US political landscape.
On the balance sheet, year-end net cash of c.US$34 million is expected, assuming US$2 million of an additional US$6 million share repurchase authorisation is executed prior to year-end (from US$29 million previously, which assumed the full US$6 million was executed). Given the expected cash position, Somero is reviewing how best to deploy capital to maximise shareholder value.
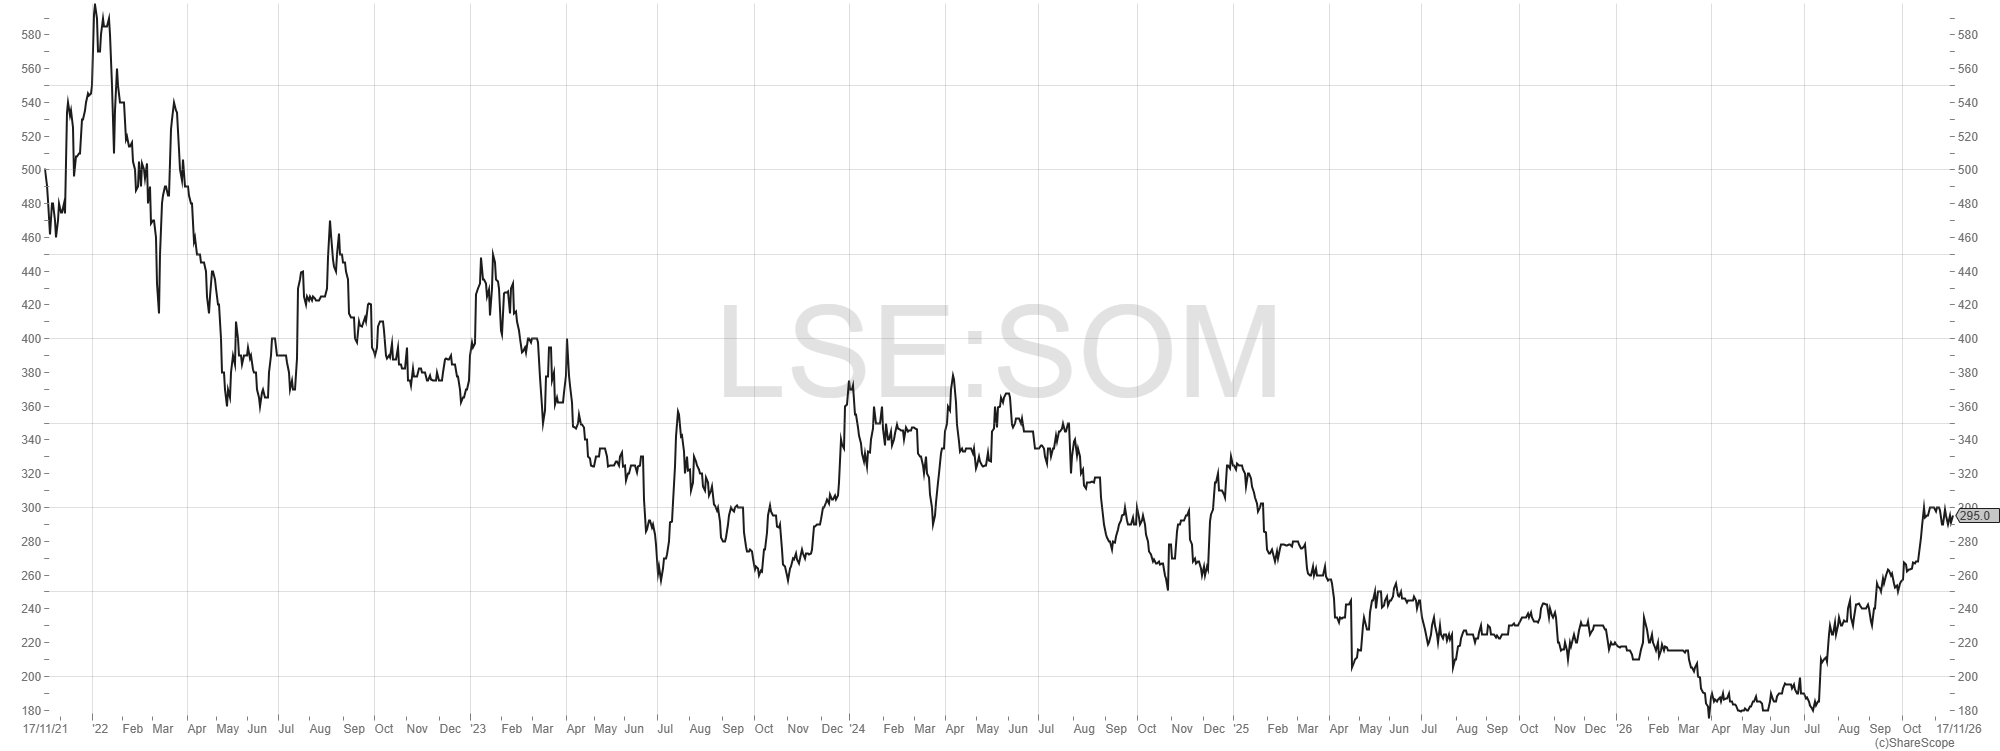
Somero Enterprises five-year share price chart
Comment
An encouraging statement from Somero which has upped its expectations once again having done so in its interim results release in September. FY2026 is set to be the first full year where revenues have not declined at Somero since 2022, with the top line having gone from $133.6 million in FY2022 to $88.9 million in FY2025.
FY2022 was the peak of a post-Covid surge, with the US$44.7 million revenue fall since then mostly coming from the North American market (US$33.7 million) and mostly one product line, boomed screeds (US$32.4 million), as higher interest rates, tight credit, labour shortages and concrete rationing pushed out project starts. The company is now making good progress under its Fortify, Innovate and Amplify strategic framework, being driven by CEO Tim Averkamp who joined in April 2025.
Expected cash of $34 million (£25.5 million) at the year end represents around 17% of the current £151.8 million market cap and could be returned to shareholders in a number of ways. Somero has a policy of making an ordinary dividend payout of 50% of adjusted net income, so it looks like the full year payment will be increased following several years of cuts. Ordinary dividends went from 50.7 cents per share in 2021 (including a special payment) to 10.2 cents in 2025. This year’s interim payment was increased by 25% to 5 cents per share but the policy is for no supplemental (special) dividend for 2026 in support of the firm’s M&A Framework. With the shares having risen from a bottom of around 174p in March this year to a current 295p, we see further share repurchases as being less likely beyond the current authorisation.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Somero Enterprises is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.