

Cybersecurity, advisory and managed security services company Shearwater Group (AIM: SWG) delivered a strong performance for the financial year to 30th June 2026, with revenues up by 34% on an annualised basis to a record £42.3 million. The FY2025 results were presented on a 15-month basis (hence the annualised measure), with FY2026 even beating this extended period’s revenues of £39.5 million.
About Shearwater
Shearwater Group is an award-winning group providing cyber security, managed security and professional advisory solutions to create a safer online environment for organisations and their end users. Its growth strategy is focused on building a scalable group that caters to the entire spectrum of cyber security and managed security needs, through a focused buy and build approach.
It operates via two divisions.
Services - delivers cybersecurity solutions through third-party software and hardware, engineering services, advisory capabilities and penetration testing. Clients are across a broad range of industries in both the public and private sectors, but recent revenues have been underpinned by clients in the telecoms and financial services sectors.
Software - Shearwater's Software division consists of two product sets:
Two related multi-factor authentication/access management tools: enabling organisations to control who can access their platforms and what permissions they have once that initial access has been granted. Flexible, highly customisable and quick and easy to deploy, these tools can be delivered either via the cloud, or installed and hosted on-premise by the client, and are currently deployed in more than 400 organisations spanning 32 countries across the globe.
The second product set is a data discovery tool, focussed on legal and compliance needs, enabling organisations to identify and manage sensitive and confidential information from across their platforms.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
FY2026 numbers
Driving the annual performance were a number of major contract wins within the larger Services business, which posted revenues up by an annualised 37% to £40.6 million. Key programmes during the year included a c.£25 million contract renewal and expansion to deliver a packet monitoring, forensic analysis and service assurance solution to a major UK-based global telecoms provider, with approximately £12.5 million of revenue recognised in FY2026. There was also a c.£9 million three-year contract renewal and expansion, with £2.7 million impacting FY2026, for a leading global financial organisation, along with a £7.3 million contract extension, with £3.5 million impacting FY2026, for a leading UK mobile network operator. While gross margins slipped slightly, from 21.6% to 18.7%, due to the structure of some of the major programmes, the division posted adjusted EBITDA profits of £3.7 million, up from £2.7 million on an annualised basis.
In the smaller Software business, trading was more challenging, with revenues falling by 17.4% on an annualised basis to £1.7 million and adjusted EBITDA down from £0.5 million to £0.2 million. Trading was impacted by competitor products, notably Microsoft's Authenticator, which is often available to clients as part of wider software packages at no additional charge. In reaction, management have taken actions including: restructuring the sales operation; removing a distribution layer in key markets, to deliver an estimated 20% uplift in the average value per transaction; and reducing annualised expenditure by £0.8 million (£0.5 million capital expenditure and £0.3 million operating expenditure). These changes, alongside investment made to improve the quality of the software products, is expected to result in an improved financial performance in FY2027.
At the group level, adjusted EBITDA was £2.6 million, an annualised increase of 44%, with an adjusted profit before tax of £1.4 million, up 186%. The statutory loss before tax reduced to £0.3 million from a loss of £13.4 million in FY2025.
On the balance sheet, Shearwater ended the year with cash of £5.6 million, a year-on-year increase of 10%, with no borrowings. Net cash generated from operating activities was £1.8 million, slightly below adjusted EBITDA due to the timing of payments on certain material contracts, in particular none of the cash related to a major contract delivered on the final day of the financial year had been collected.
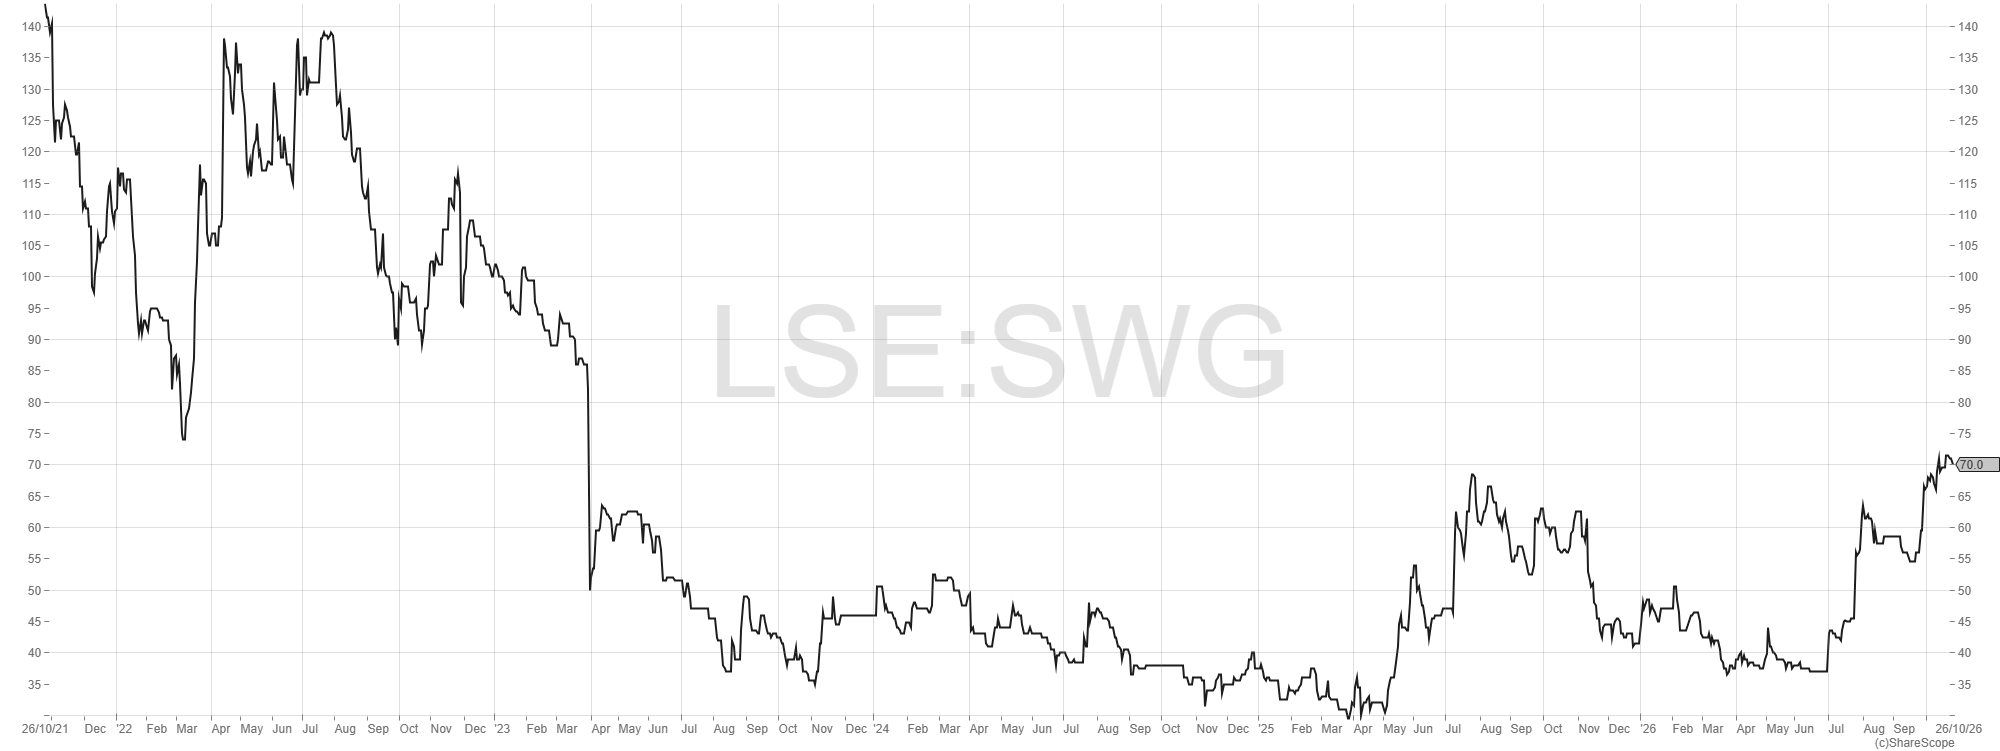
Shearwater Group five-year share price chart
Outlook
Shearwater was upbeat about the trading environment, which is being driven by growth in the frequency and complexity of cyber threats, resulting in what the firm calls a “robust pipeline”. Trading so far in FY2027 is said to be in line with expectations, with new contracts including a £1.2 million new client win with one of Japan's largest financial groups to provide core email protection technology, and a £1.7 million, two-year contract renewal and expansion to provide advanced threat intelligence platform to a central government department. At this early stage, Shearwater believes it is well positioned to deliver FY2027 results in line with market expectations.
Comment
These record results from Shearwater were very slightly ahead of the upgraded expectations given in the firm’s July trading update. Despite this, the shares have slipped by 5% on the news to currently trade at 66.5p.
Revenues grew strongly in FY2026, and despite the gross margin slippage, overall profits are benefitting from operational gearing. Notably, underlying administrative expenses of £5.8 million were actually down by 1% on an annualised basis, representing a second consecutive small year-on-year reduction, achieved despite 74% revenue growth across the two years.
Structural growth in the company’s markets continues to provide opportunities, with many recent high-profile cybersecurity incidents demonstrating the damaging consequences of inadequate cyber resilience. To give some recent examples:
- On 11/12th October 2026 an unknown party accessed refrigeration controllers at up to 700 French supermarkets and set them to defrost mode overnight. Temperatures in fridges and freezers were pushed as high as 50°C, spoiling food and causing fires at several stores.
- In early October, online fashion seller ASOS was subject to a hack by the Xuanye Group via a third party communications platform. Data including customer names, addresses, phone numbers and emails were taken, but no payment or password data. The attackers hijacked ASOS’s own app to publicise the breach, forcing the company to make an announcement to the stock market. The incident caused reputational damage and the shares to fall by around 10% in value.
- Japan's GMO Internet Group disclosed a major cyber-attack in late October that resulted in unauthorised access to its Onamae.com remote desktop platform, with 26,739 servers potentially affected. This resulted in the breach of customer data and unauthorised foreign exchange trades being executed. GMO said in a statement released today, (27th October) “We have received a notice from the suspected attacker that they will release customer information and launch a ransomware attack at 12:00 PM on Tuesday, October 27th.”
This handful of examples (from October alone) demonstrate that cybersecurity will remain a defining challenge for organisations round the world, and a growth opportunity for Shearwater. To give a few forecasts, Fortune Business Insights valued the global cybersecurity market at c.US$219 billion in 2025 and expects it to increase from US$248 billion in 2026 to US$699 billion by 2034, that’s a compound annual growth rate of 13.8%. In the UK, Mordor Intelligence estimates that the cybersecurity market will grow from US$18.36 billion in 2026 to US$30.19 billion by 2031, representing a compound annual growth rate of 10.46%.
Shearwater also sees a continuing and significant opportunity in the public sector. This is something expected to accelerate following publication of the UK Government's defence spending plans, reflecting the growing recognition that resilient digital infrastructure and cyber defence are critical components of national security. We also note recent comments from Sir Ken McCallum, Director General of MI5, who highlighted increasing cyber threats in the intelligence body’s recent annual threat update.
Shearwater is currently capitalised at just £15.7 million, with net cash as at 30th June 2026 covering 36% of that. This positions the firm well to take advantage of any opportunities that arise, and also to potentially pay a dividend in the near future. Earlier this month, the firm received support from shareholders for the first stage of a proposed capital reduction programme, which will allow the payment of a dividend and/or a share buyback programme.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Shearwater Group is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.