

Ahead of its AGM, the AI-powered loyalty and promotions platform provider Eagle Eye (AIM: EYE) has announced that FY2027 (to end June) has started positively. Four new contracts have been secured in the new financial year to date, which the company says demonstrates continued commercial momentum and growing demand for its loyalty and AI-powered promotions capabilities across international markets.
Two international wins were previously announced in October, with supermarket chains Stater Bros in the US and Auto Mercado in Costa Rica. Once live, the two contracts are together expected to generate initial base annual recurring revenue of c.£0.8 million with the potential to deepen the accounts over time.
The two other multi-year contracts are with Carrefour Belgium, for EagleAI's Personalised Challenges solution, and with one of Australia’s leading pharmacy networks, secured through a new multi-year marketing agreement with a regional pharmacy data and analytics partner.
Elsewhere, a significant renewal has also been secured with Australia’s largest retail drinks network & portfolio of licensed hotels, to extend its highly successful loyalty programme across further banners.
Eagle Eye also flagged the launch of Personalised Picks, a new AI-powered capability that helps retailers make existing promotions more relevant to individual customers. In its first deployment with a large European grocer, the solution is said to have delivered 3.5 times as many featured promotions purchased compared with a generic promotions mailer. Encouraging for new customer wins, the solution can be deployed in as little as six weeks, with no point-of-sale integration required.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
The business
Eagle Eye is an AI-powered loyalty and promotions platform, enabling the world's leading retailers, grocers, hospitality and travel brands to earn lasting customer loyalty through real-time personalised engagement. The platform embeds AI natively, combining enterprise-grade loyalty and promotions capability with built-for-purpose intelligence to deliver 1:1 personalisation to millions of customers globally.
The firm’s growing international customer base includes the likes of Loblaws, Giant Eagle, Wakefern, Asda, Tesco, Morrisons, JD Sports, E.Leclerc, Carrefour and the Woolworths Group. Each week, more than 1.8 billion personalised offers are executed via the platform, and over 800 million loyalty member wallets are managed worldwide.
In June 2025 the company had to deal with the loss of a contract with digital incentives company Neptune Retail Solutions (NRS), which had an annual value of between £9 million and £10 million in revenue, for the provision of digital promotional services to a national US grocer. For the 2026 financial year Eagle Eye reported revenues up by 21% to £46.1 million (excluding the NRS contract loss) as it secured 13 major customer wins, across three continents, including entry into the airline sector with easyJet and the addition of a major global brand with Subway. However, including the NRS contract loss, revenues were down from £48.2 million. Adjusted EBITDA for FY2026 was £9.8 million, ahead of initial expectations but down from £12.2 million in 2025.
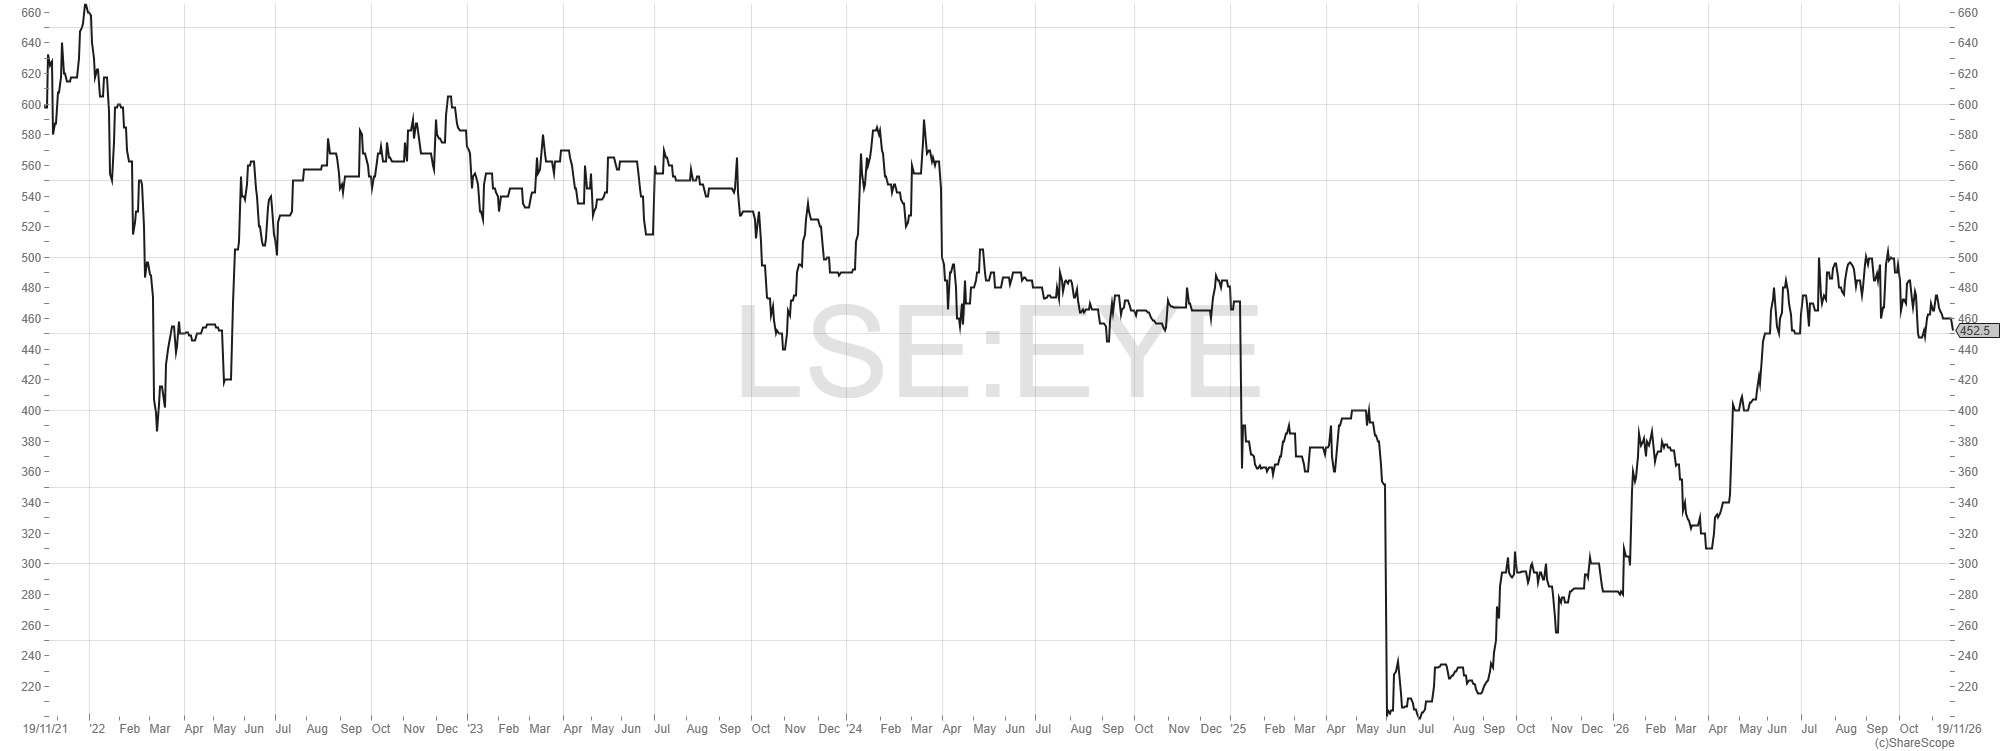
Eagle Eye five-year share price chart
FY2027 outlook
In today’s update Eagle Eye added that the positive start to FY2027 underpins confidence in delivering results in line with market expectations, representing a return to double-digit growth in revenue and adjusted EBITDA. The firm said that it is well positioned to achieve its medium-term ambitions of £100 million annual revenue and an adjusted EBITDA margin of over 30%. This is planned to be achieved through further international sales expansion, scaling its OEM and partner channels and enhancing its AI-powered loyalty and promotions capabilities, to meet growing global demand for personal customer engagement.
Comment
Eagle Eye is making good progress in FY2027 to date and recovering from the big contract loss in 2025, as well as an additional profit warning made in January that year. Following the recent string of new contracts, the shares have recovered from lows of around 192p in June last year to a current 452.5p, almost back to levels seen just before the January 2025 profit warning.
Underpinned by £44.5 million of annual recurring revenue at the end of June 2026, the firm’s ambitious medium-term targets imply that revenue could more than double from 2026 levels and adjusted EBITDA could more than treble.
The company had net cash of £16.1 million as at 30th June 2026 and has recently commenced a share buyback programme of up to £1 million. Eagle Eye has commented that it believes the current share price substantially undervalues the business and its future prospects and that the programme represents an effective use of cash balances to deliver value for shareholders.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
Eagle Eye is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.