

Sofa seller DFS Furniture (LSE: DFS) has announced that tough trading conditions reported at the time of the firm’s full year results on 24th September have continued. Back then, DFS reported that order intake over the first 12 weeks of FY2027 was -2.5% year on year, in line with expectations and reflecting the weak consumer backdrop. Over the subsequent seven weeks, upholstery market demand is said to have softened further, reflecting continued pressure on household budgets and reduced consumer confidence.
While no figures were given, DFS said that it has not been immune to this climate, but proprietary banking data indicates that core retail brands, DFS and Sofology, have continued to outperform the wider sector.
Get our research notes free, the day they're published
In-depth coverage of UK small caps and junior miners. Email only, unsubscribe any time.
The business
DFS Group is the leading sofa retailing group in the UK, operating across the two retail brands of DFS and Sofology, offering a differentiated service and innovative product ranges, that have broad appeal across different customer segments and demographics.
DFS is the leading retailer and manufacturer of sofas in the UK and operates through integrated retail channels, with 115 showrooms in the UK and Republic of Ireland, and its e-commerce platform. Sofology is the third largest sofa retailer in the UK, having 56 showrooms in the UK and Republic of Ireland alongside its e-commerce platform. The brand appeals to a style conscious customer, willing to invest their time and money on their perfect sofa, with the average order value for Sofology being c.30% higher than DFS.
Trading outlook
DFS added that ahead of the key trading periods of Black Friday and the Winter Sale, the company is investing to support customers in this challenging environment with targeted commercial initiatives, whilst maintaining rigorous discipline across the cost base. The firm expects that, given the circumstances, full-year profit expectations have a wider range of potential outcomes. While no specific range was given, a further update will be provided as part of a half year trading statement on 21st January 2027.
Elsewhere, the firm is expanding its non-upholstery Home business by using additional space in its showrooms through mezzanine expansion. Back in September, DFS said that it was confident that it can deliver an incremental £100 million in revenue over the medium term from this initiative. Following the launch of a fifth mezzanine at the DFS Leeds Birstall showroom in October, early customer response is said to have been encouraging and the showroom is trading in line with expectations.
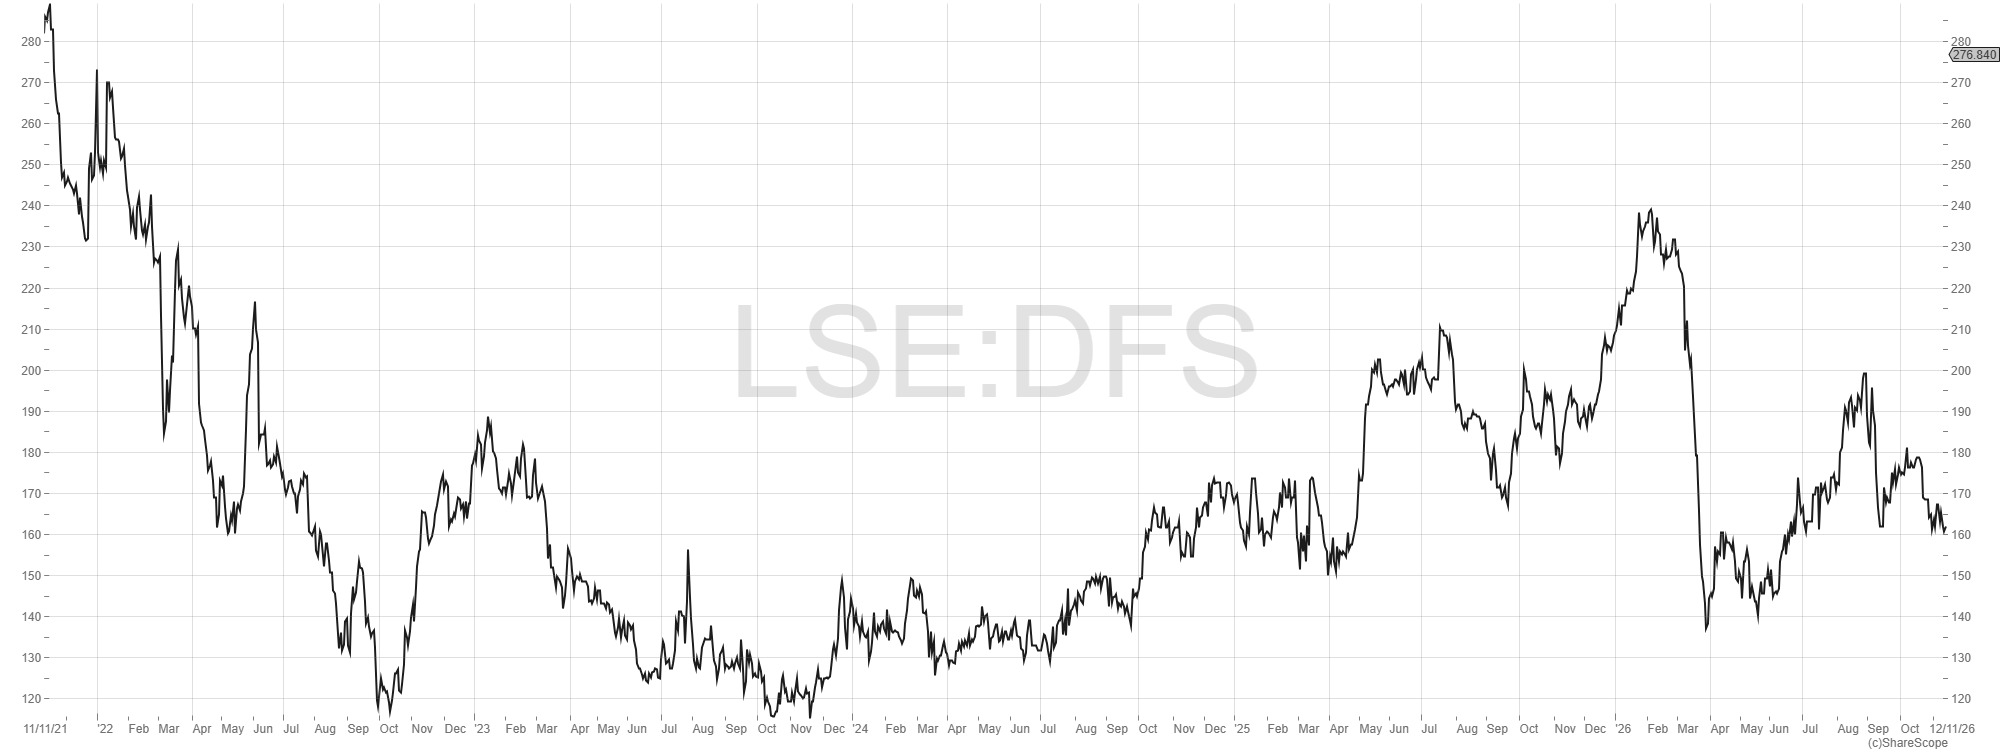
DFS Furniture five-year share price chart
Comment
Challenging times for DFS, which is having to contend with a number of negative pulls on the business including reduced consumer confidence, higher raw material and freight costs. This is a business which operates on very thin margins, with underlying pre-tax profits in the last financial year of just £44.9 million on revenues of £1.06 billion. In its recent full year results, the company reaffirmed its confidence in achieving medium-term targets of £1.4 billion of revenue and 8% PBT margins, which would imply that it thinks £112 million of annual pre-tax profits are achievable, 149% higher than last year’s result. While the new mezzanine stores and further rollout of Sofology stores could provide some relief in the near term, investors are really looking for a solid recovery in the core upholstery market before those targets can be hit.
Sign up to receive our full investment research notes on small cap growth companies, as soon as they are published.
Disclosures
DFS Furniture is not a corporate client of Optimo Research Ltd.
Disclaimers
This article, and all articles on the Optimo Research blog, are for information purposes only. Our blog articles do not constitute an investment recommendation or personal advice. Nothing in our blog articles should be construed as an offer or the solicitation of an offer to buy or sell securities by us and, as we have no knowledge of your individual situation and circumstances, you should not make any investment decision without consulting a fully qualified financial adviser. Your capital is at risk by investing in the financial instruments issued by the companies discussed. For full disclosures, disclaimers and risk warnings click here.